
Running a business can make personal financial planning more complicated. You may need to pay employees, manage cash flow, reinvest profits, save for retirement, and plan for your family’s future at the same time. A financial advisor for business owners can help connect these responsibilities and build a financial plan around your business and personal goals.
The right advisor can help you plan owner compensation, manage investments, review retirement options, prepare for a future business sale, and coordinate with your CPA or attorney. However, not every advisor provides all these services. Before hiring one, understand what you need, compare fees, and check the professional’s qualifications, responsibilities, and possible conflicts of interest.
Direct Answer
A financial advisor for business owners helps coordinate business-related financial decisions with personal goals such as saving, investing, retirement, risk management, and a future sale. Services, fees, and professional duties vary.
Experience
Practical Finance Tip: Before comparing advisors, write down the decisions you need help with and ask each provider to price the same scope of work. A low fee may cover fewer services, and the right professional may be a CPA or bookkeeper rather than an investment advisor.
What Does a Financial Advisor Do for Business Owners?
 A financial advisor helps you make decisions about your money based on your goals, available resources, and financial risks. For a business owner, that work may include both company-related planning and personal financial decisions.
The exact service depends on the advisor’s experience and the agreement you sign.
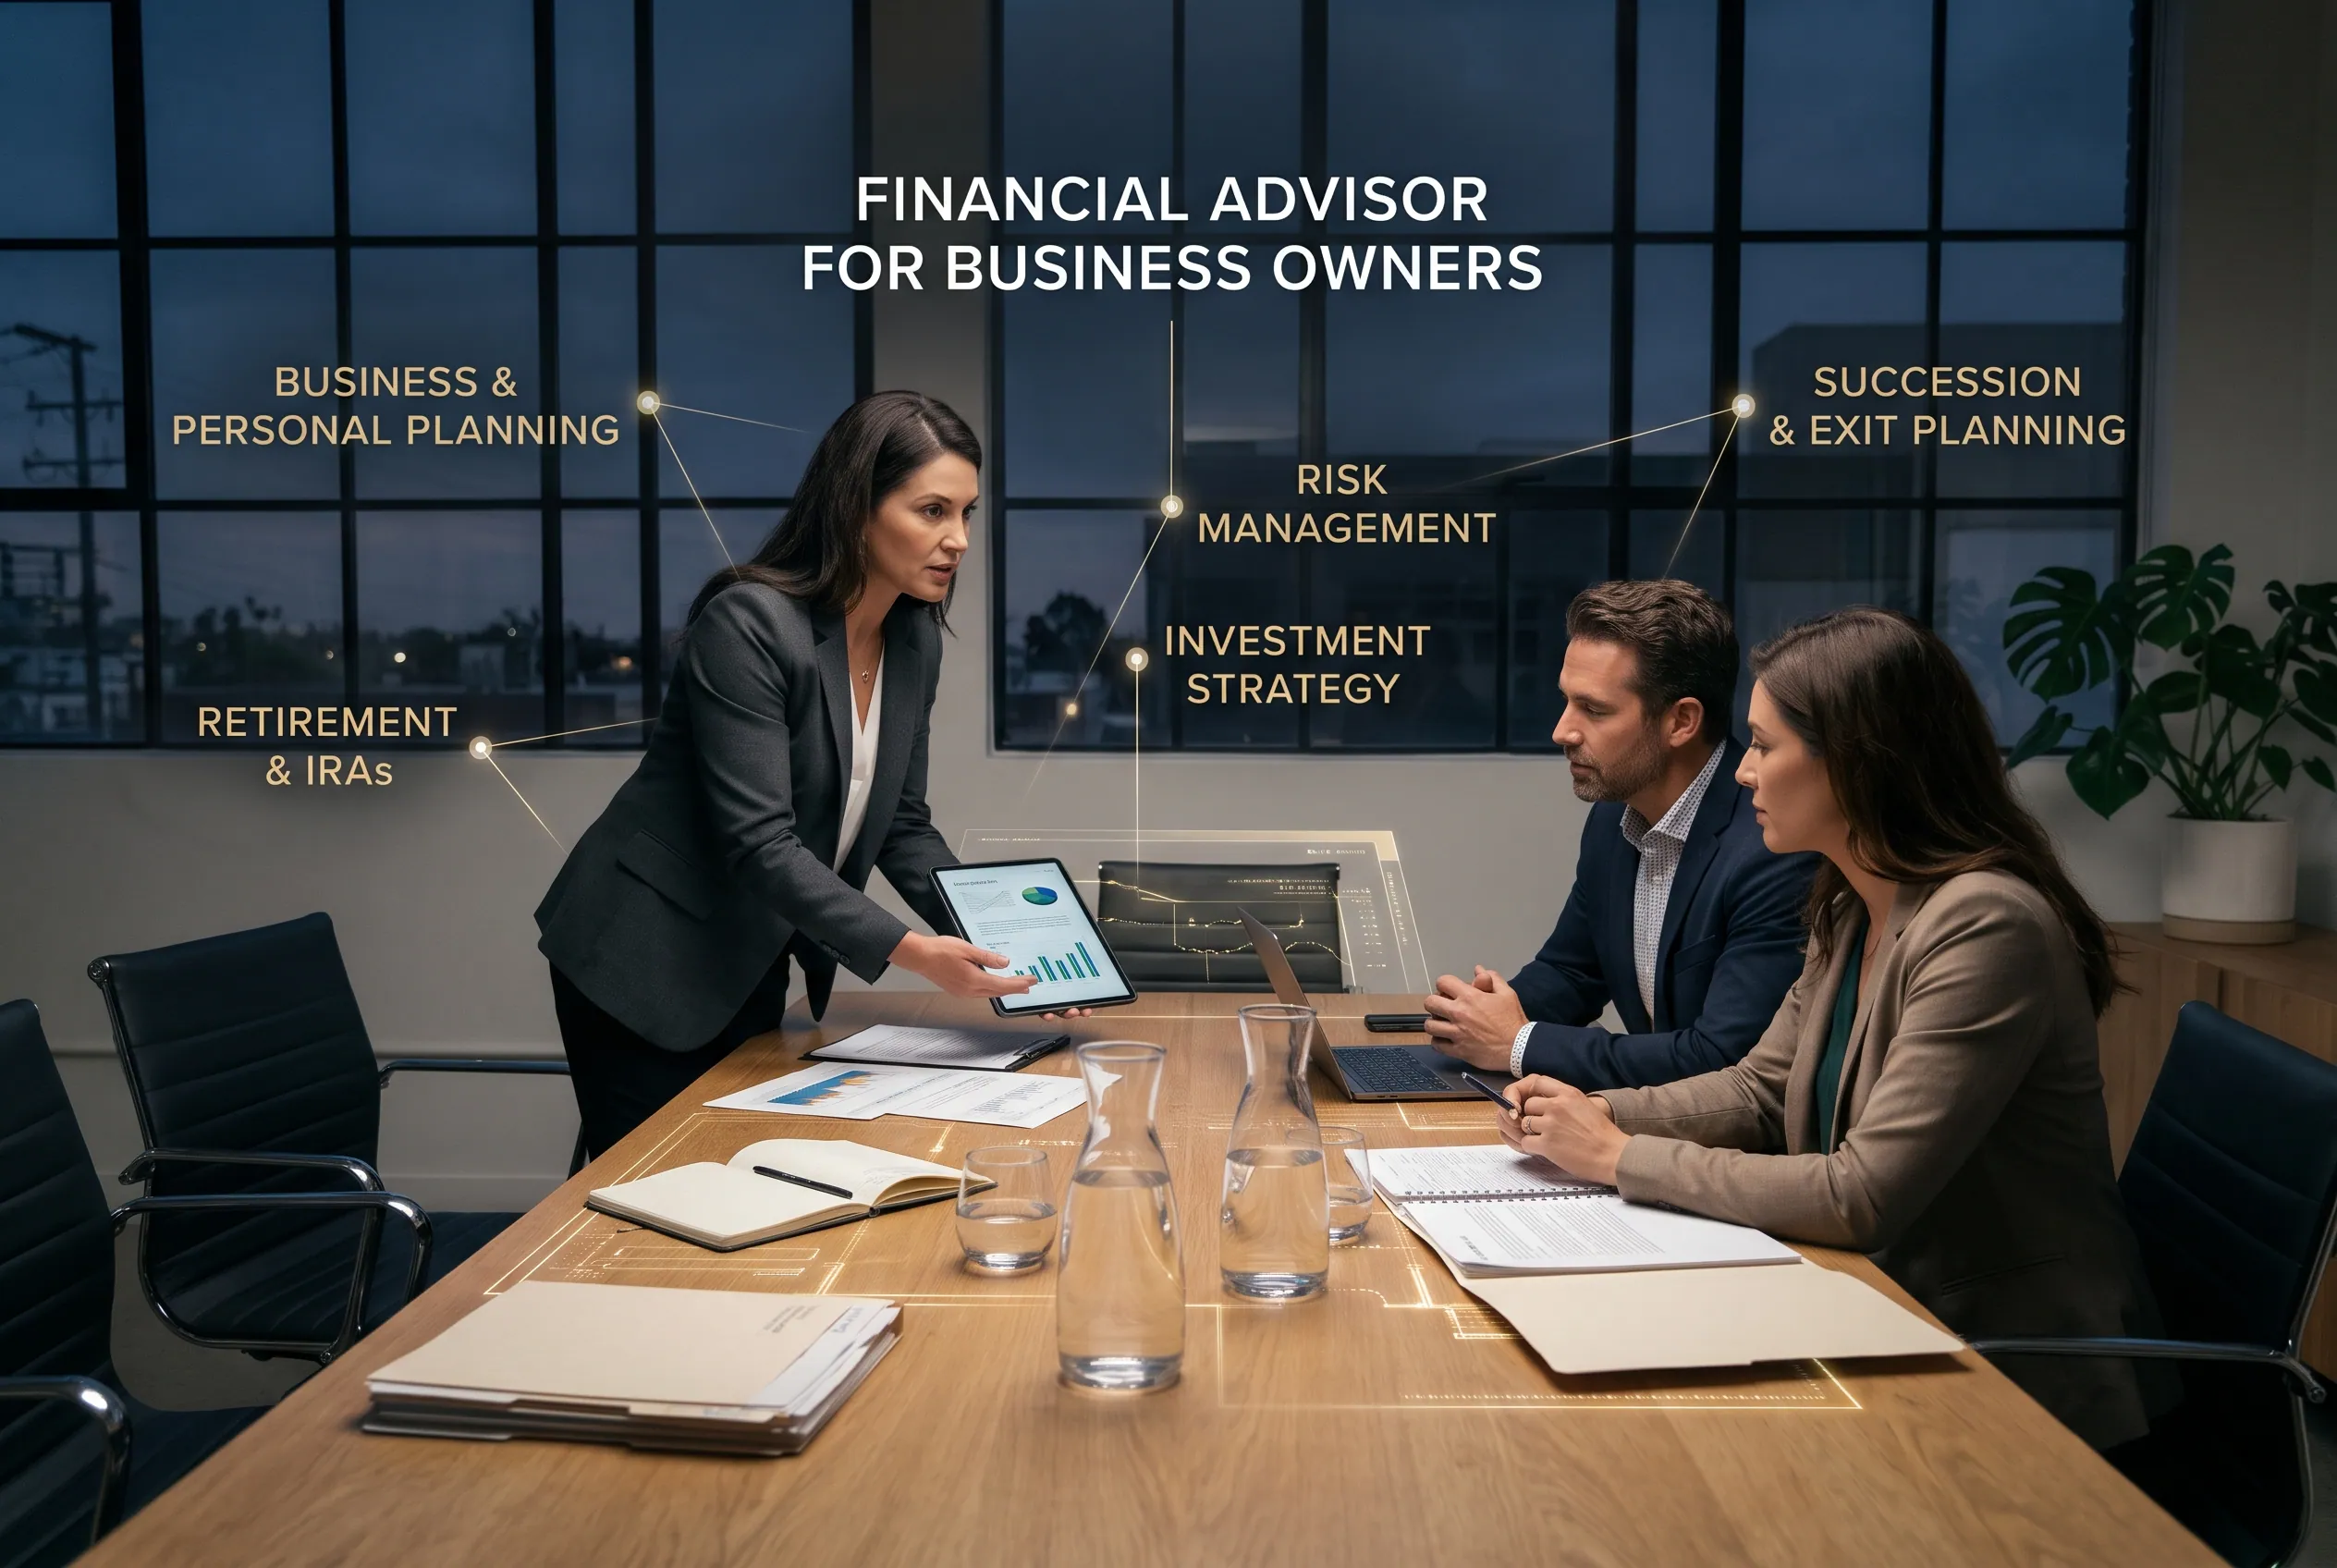
Common areas of support include the following.
Business and personal financial planning: An advisor can help you consider how much money to keep in your company, how much to take as compensation or distributions, and how to fund personal goals. Tax and legal consequences may require help from your CPA or attorney.
Retirement planning: Business owners may not have access to a traditional employer-sponsored retirement plan. An advisor can help compare suitable options, such as a SEP IRA, SIMPLE IRA, or individual 401(k), depending on eligibility and business circumstances.
Investment planning: If you have money available to invest outside your business, an advisor may help develop an investment plan that reflects your time horizon, goals, and willingness to accept losses.
Risk management: An advisor may help identify gaps in your financial plan, including dependence on business income, insufficient personal reserves, or a lack of retirement savings outside the company. Insurance and legal arrangements may need separate specialist advice.
Succession and exit planning: If you plan to sell your business, transfer it to family members, or retire, an advisor can help coordinate financial preparation and estimate how different outcomes could affect your personal wealth.
The value comes from connecting these decisions, not simply recommending investments.
For example, imagine that your business earns a profit but needs most of its cash to pay suppliers and employees. Taking a large amount of money out for personal investing could leave the company short of working capital. An advisor may help you review the competing goals, while your accountant verifies the relevant accounting and tax effects.
When Should a Business Owner Consider Hiring a Financial Advisor?
You may benefit from financial planning when your decisions become too connected or complicated to manage confidently on your own.
Consider speaking with an advisor if:
- Your business generates income, but you are unsure how much to save personally.
- You have most of your wealth tied up in the company.
- You want to create a retirement plan for yourself or eligible employees.
- You are considering selling the business or transferring ownership.
- You need help coordinating investments, retirement, insurance, and long-term goals.
- You have several financial professionals but no clear process for coordinating their work.
You do not need to wait until your business reaches a particular revenue level or you have a large investment portfolio. Some advisors offer hourly or one-time planning services, while others require an ongoing relationship or minimum level of assets.
However, a financial advisor may not be your first priority if your main problem is missing financial records, unpaid bills, or uncertainty about the company’s current cash position.
In that situation, a bookkeeper, accountant, or virtual CFO may be more useful. Once your records and immediate business finances are in better order, you can decide whether broader planning would add value.
A practical starting point is to write down the two or three financial decisions that concern you most. This helps you find a professional whose services match your needs rather than paying for a broad package you may not use.
How an Advisor Connects Business Finances With Personal Wealth
 Business owners sometimes treat the company and their personal finances as separate worlds. Legally and operationally, they may need to be kept separate. Financially, however, the decisions often affect each other.
PNC’s Business Owner Wealth Insights 2026 report, based on a PNC-sponsored survey of 300 middle-market business owners, found that 89% wanted financial advice that considered both business and personal needs. This result reflects that survey’s participants, not every business owner in the United States.
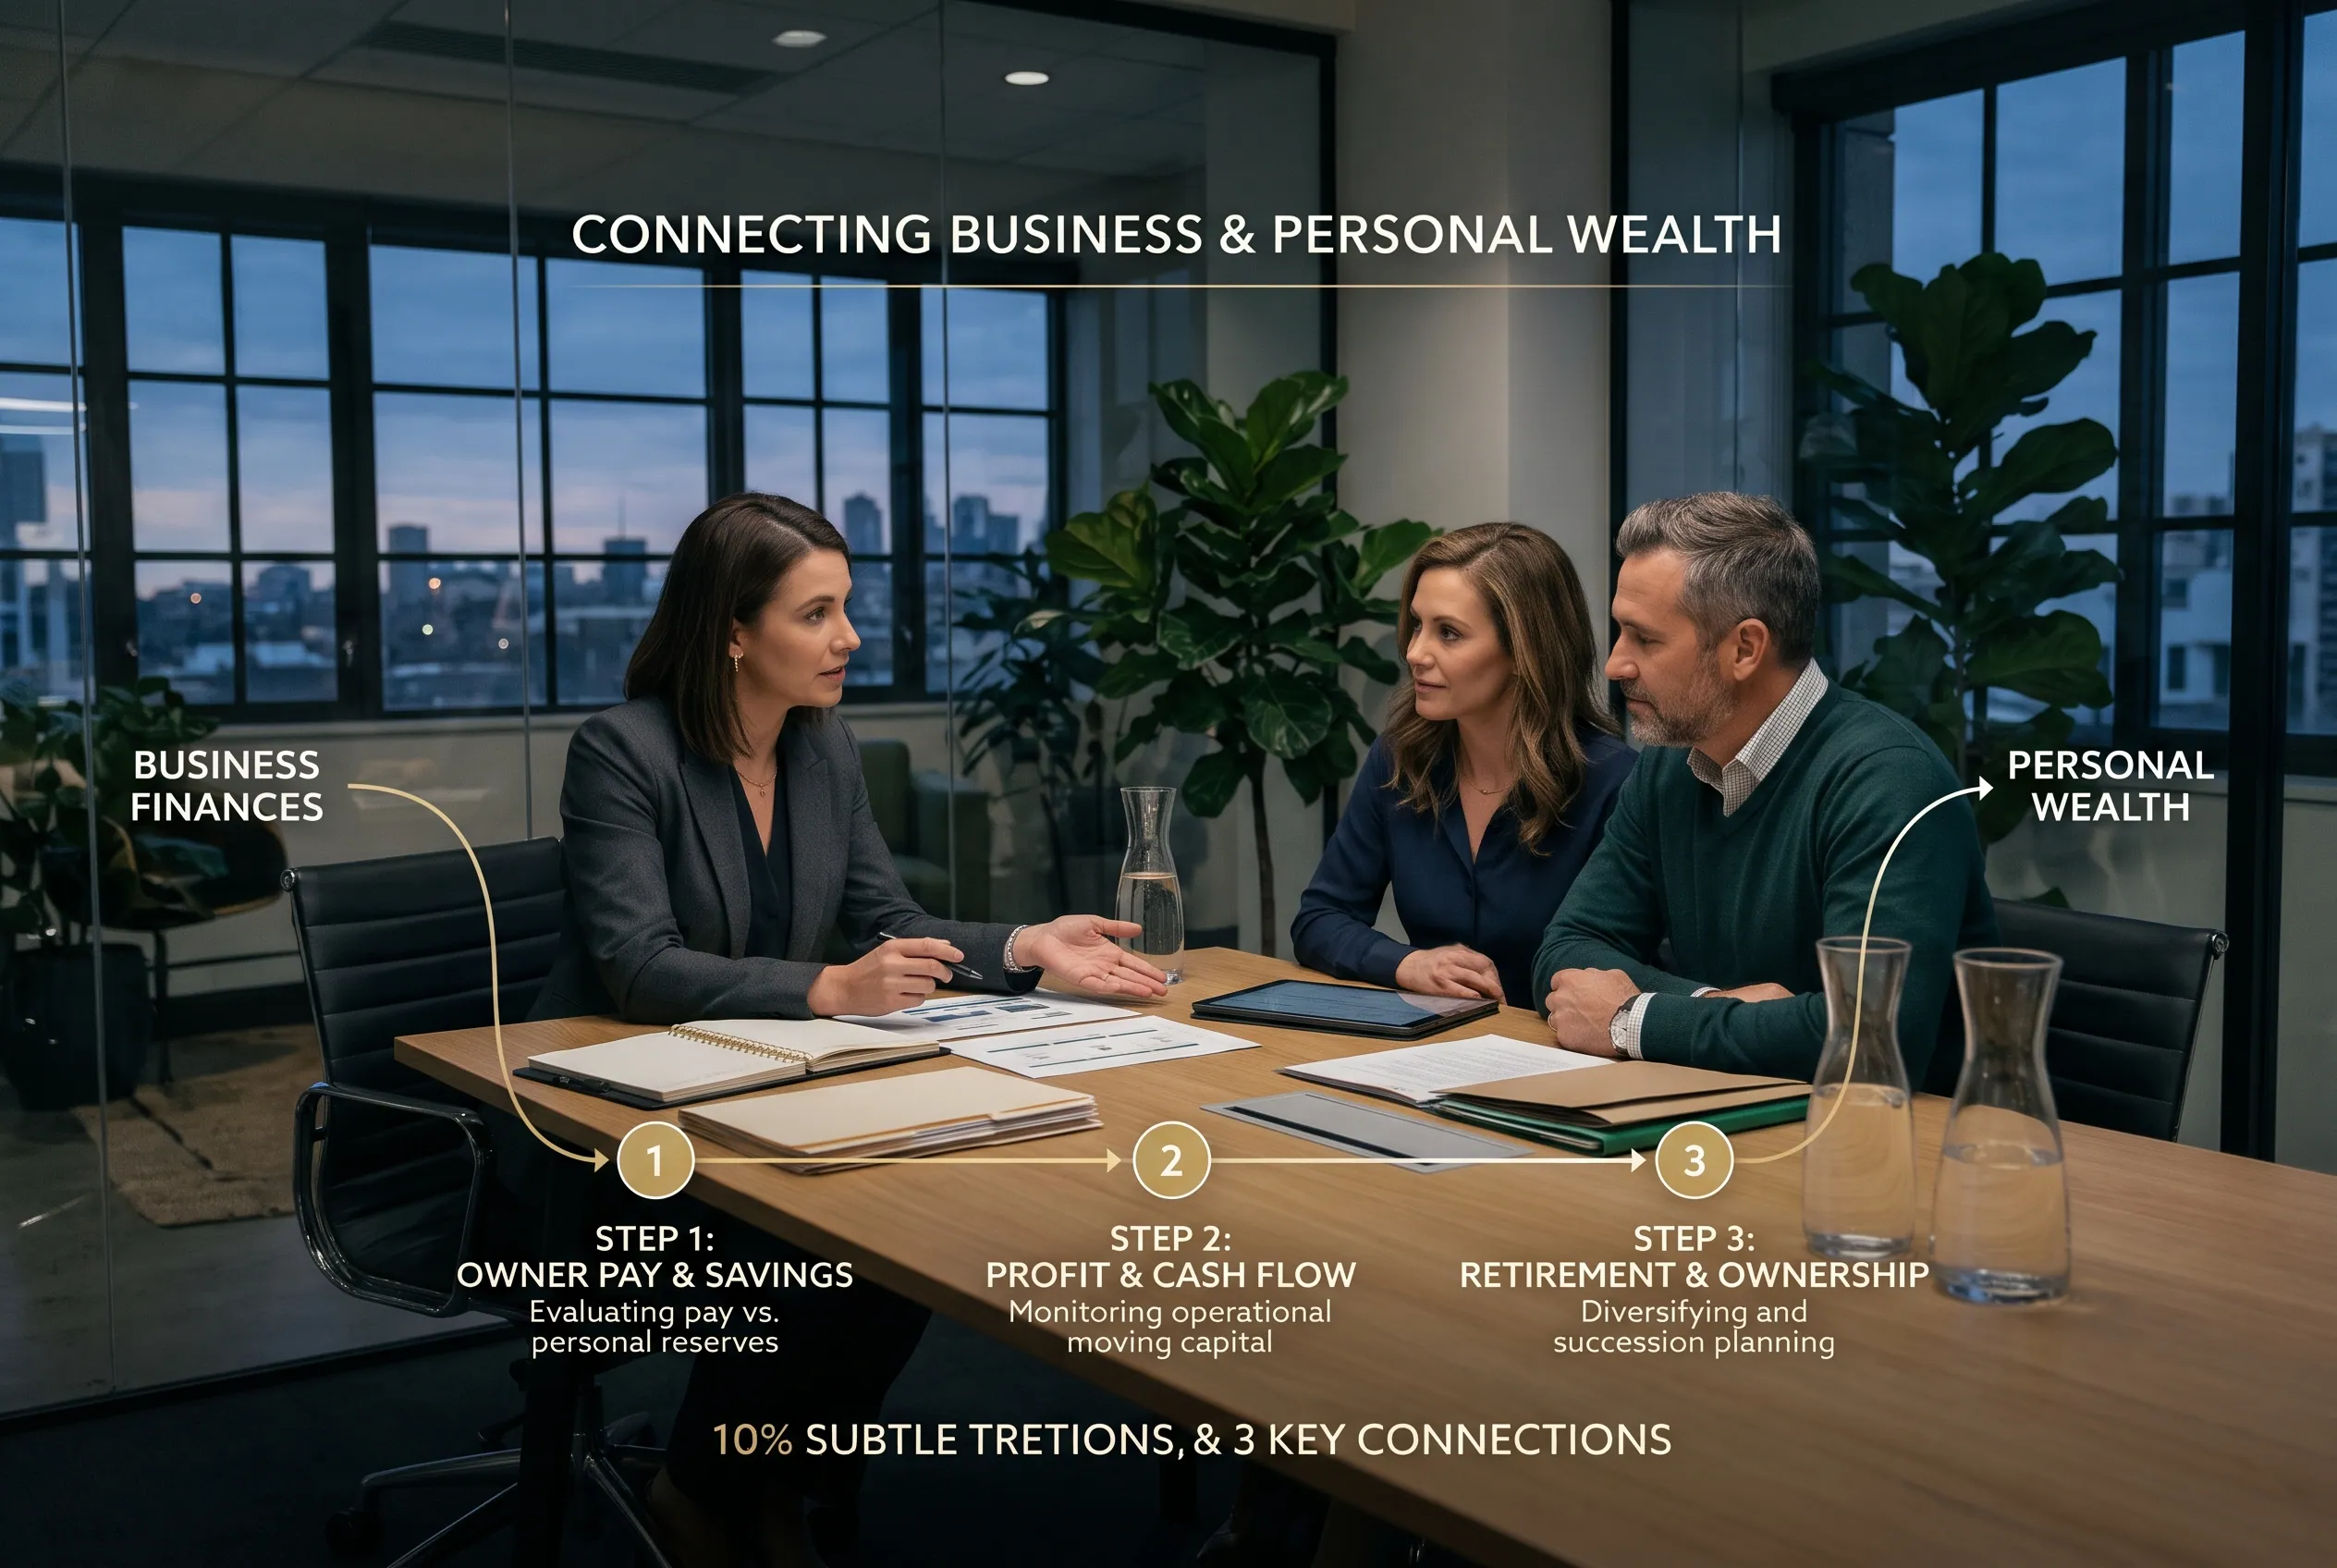
Here are three important connections an advisor may help you consider.
1. Owner pay and personal savings
Your business may need money to purchase equipment, hire employees, or cover seasonal costs. At the same time, you need money for household expenses, emergencies, and future goals.
A financial plan can help you evaluate a reasonable approach to owner compensation and personal saving. The actual amount and method depend on your business structure, cash needs, tax circumstances, and other factors.
Avoid taking out money simply because the business account shows a high balance. Some of that cash may already be needed for taxes, payroll, supplier payments, or upcoming expenses.
2. Business profit and cash flow
Profit and cash flow are not the same thing.
Profit measures income after expenses under the applicable accounting method. Cash flow shows money moving into and out of the business. A company can report a profit while struggling to pay bills because customers have not paid their invoices or money is tied up in inventory.
An advisor may help with the broader financial plan, but the business still needs reliable accounting records and cash-flow forecasts. Your accountant or virtual CFO may be better placed to prepare or verify those details.
Before moving substantial money from the business into personal investments, make sure you understand upcoming obligations, required reserves, and any tax or legal consequences.
3. Retirement and future ownership
If much of your wealth depends on your business, your retirement may depend on its future value and ability to produce income. That creates concentration risk: too much of your financial future depends on a single asset.
Depending on your circumstances, a plan may combine business reinvestment, personal savings, retirement accounts, and other investments. Diversification can reduce dependence on one asset, but it cannot eliminate investment losses or guarantee retirement income.
A future business sale also deserves early attention. The US Department of Labor’s succession-planning guidance suggests that starting five to ten years before a planned exit can give owners time to explore options. This is planning guidance, not a required deadline.
Your advisor may coordinate with a CPA, business valuation specialist, and attorney to evaluate a sale, family transfer, or employee ownership option. Each professional handles different parts of the process.
Financial Advisor vs. CPA, Bookkeeper, and Virtual CFO
These professionals may work together, but their main responsibilities differ. Hiring the right one depends on the problem you need to solve.
| Professional | Main focus | When to consider one |
| Financial advisor | Personal financial planning, investments, retirement, and wealth or exit planning | You need help making connected long-term financial decisions |
| CPA or accountant | Accounting, tax preparation, financial reporting, and other agreed services | You need accurate records, tax support, or accounting guidance |
| Bookkeeper | Daily transactions, invoices, payments, and account reconciliation | You need organized and up-to-date financial records |
| Virtual CFO | Financial forecasts, performance measures, cash planning, and operating decisions | Your business needs higher-level financial management without a full-time CFO |
A CPA may also provide strategic tax planning, business consulting, or financial planning if those services fall within their expertise and agreement. A financial advisor may have tax knowledge, but you should not assume they provide tax preparation or legal advice.
Similarly, some virtual CFOs help with strategic planning beyond accounting, and some financial advisors have experience working with business owners. Titles alone do not define the exact service.
If you already work with a CPA, ask what planning support they provide before paying another professional. You may need an advisor to fill a specific gap, not duplicate work that someone already handles.
How Much Does a Financial Advisor Cost for Business Owners?
 There is no single price for business-owner financial advice. Your total cost depends on the advisor’s payment model, the services included, the complexity of your situation, and whether you need ongoing support.
Published fee data provides a useful starting point.
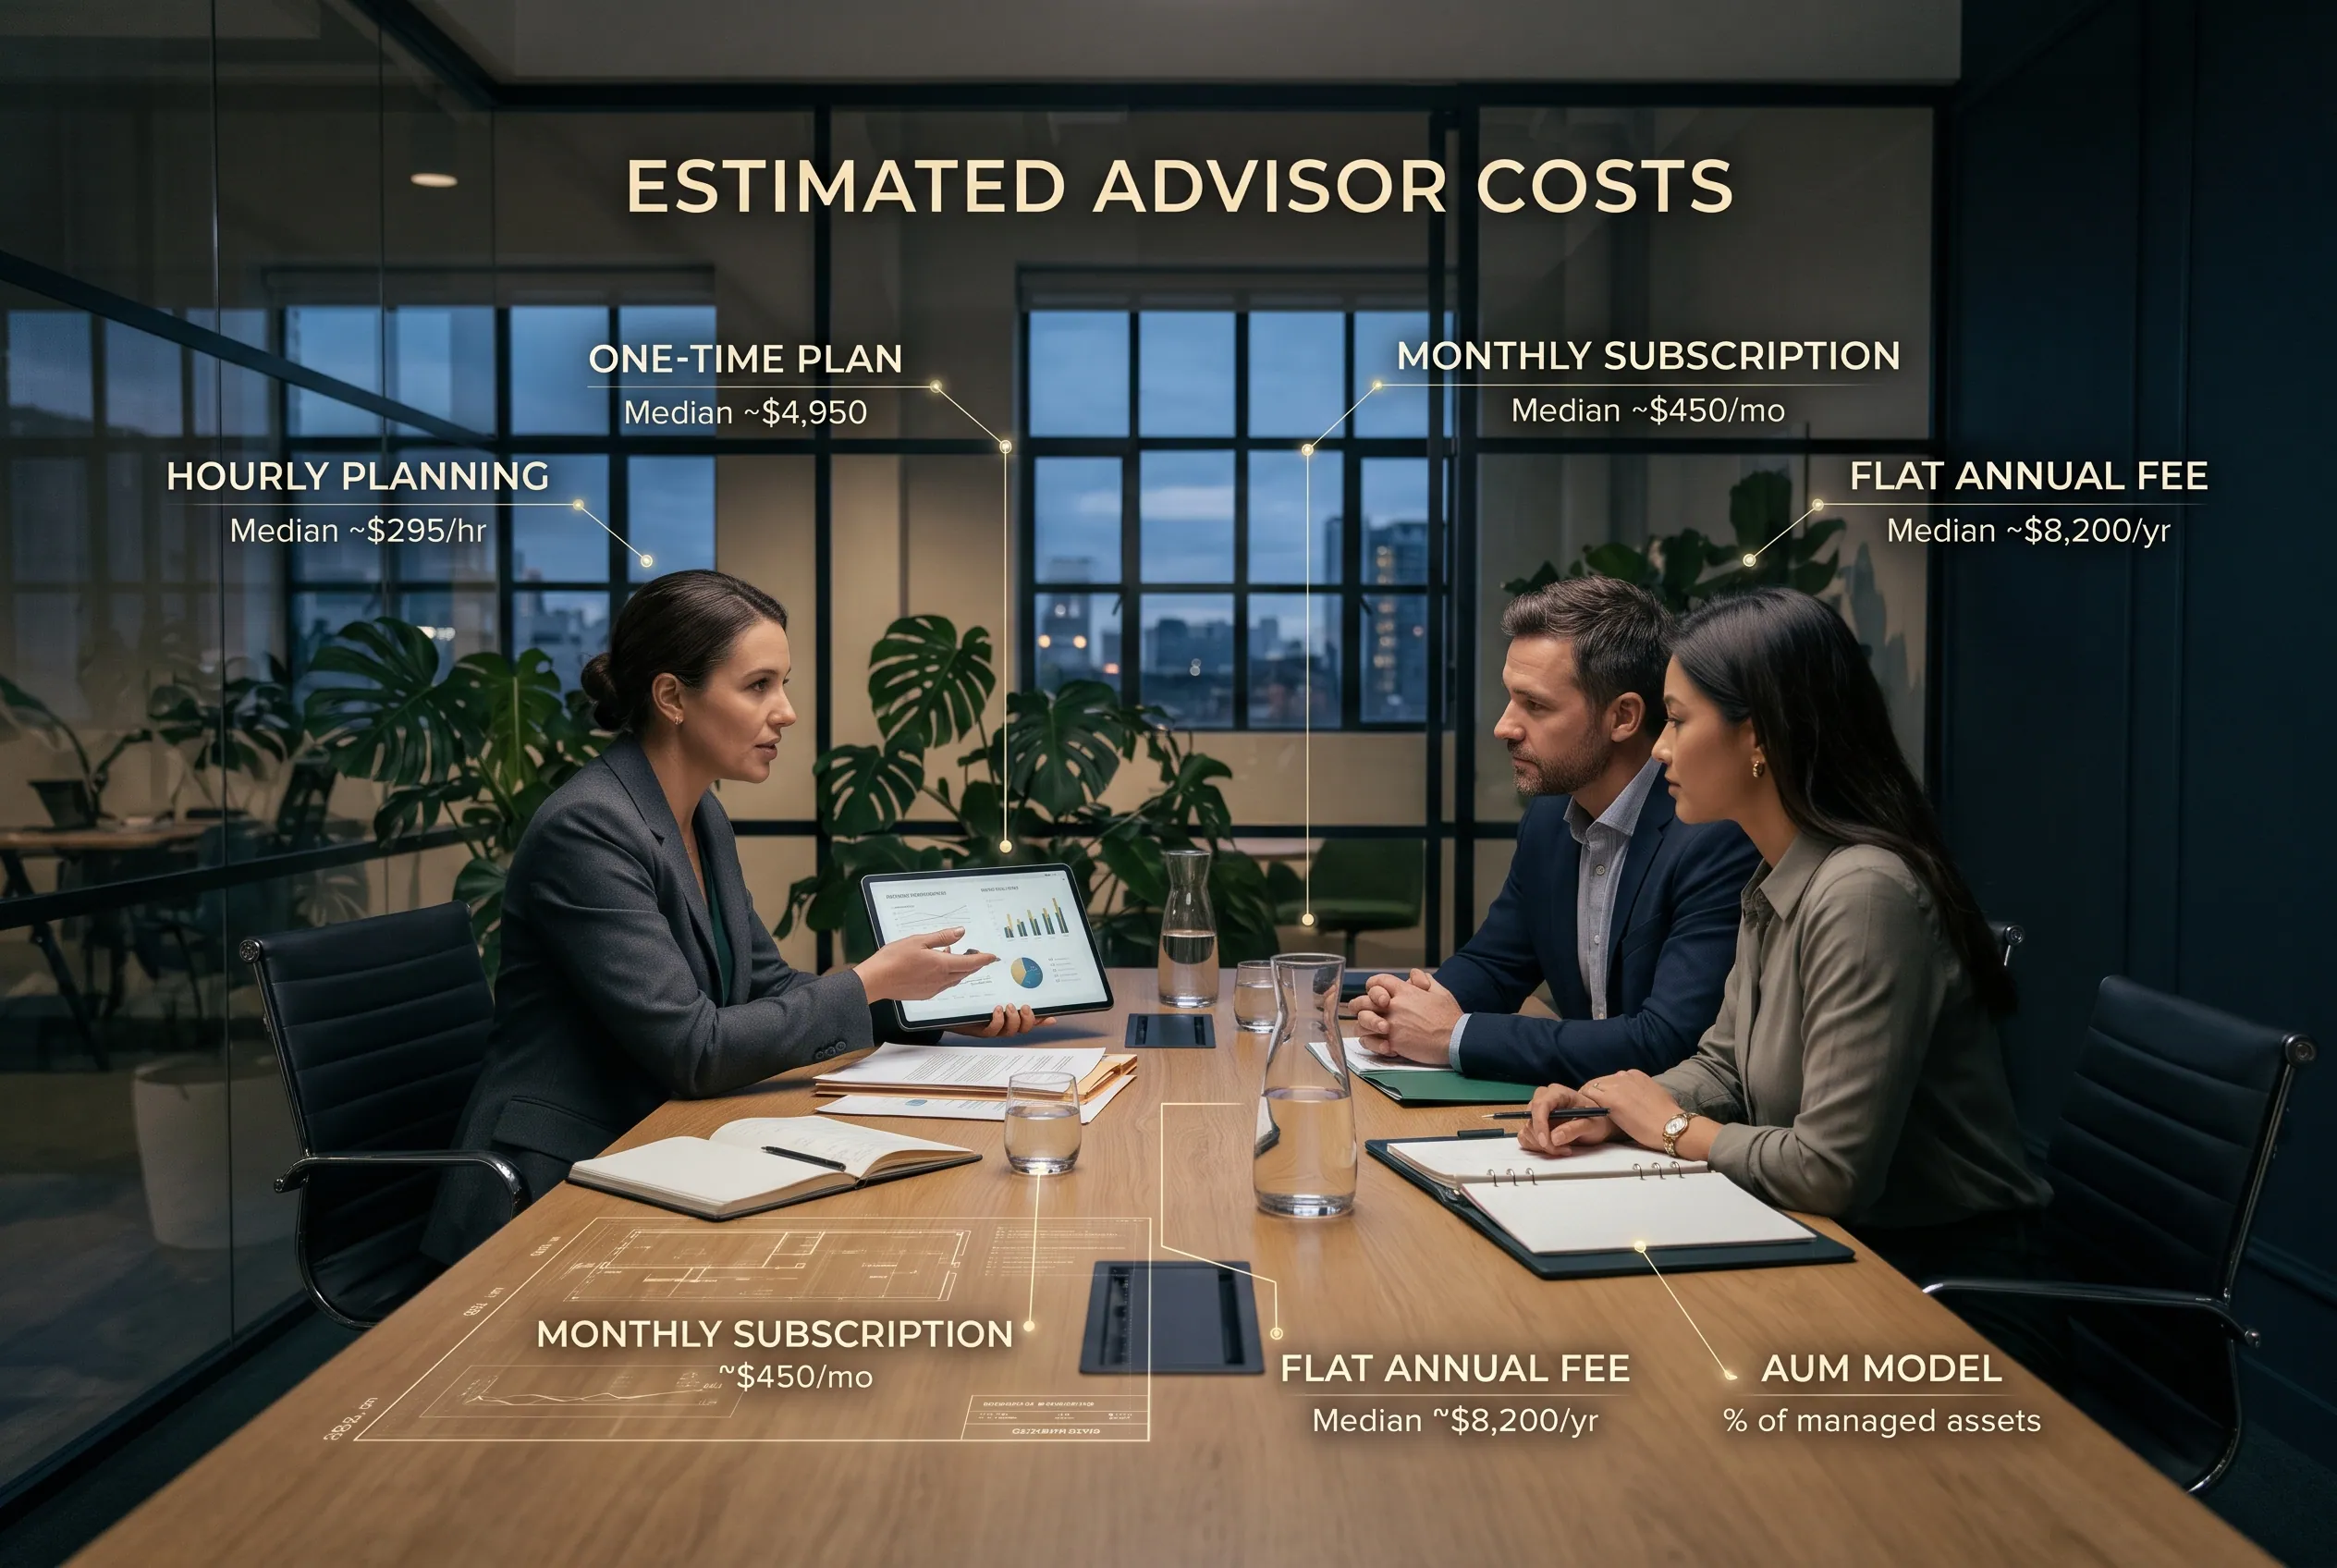
According to PlannerFees’ October 2026 analysis, which examined published fee schedules in regulatory filings for US fee-only financial planning firms, the reported figures were:
| Fee type | Median published fee | Middle half of firms |
| Hourly financial planning | $295 per hour | 225–350 per hour |
| One-time financial plan | $4,950 | 2,700–7,050 |
| Monthly subscription planning | $450 per month | 250–800 per month |
| Flat annual advisory fee | $8,200 per year | 5,000–15,500 per year |
The figures cover different groups of firms and are not prices specifically for every business-owner advisor. They are published fee benchmarks, not quotes or guarantees of what a particular reader will pay. The scope of work can differ significantly between providers.
Common financial advisor fee models
Assets under management (AUM). The advisor charges a percentage of the investments they manage. If the annual fee is 1% on a $100,000 portfolio, the fee would be $1,000 for a full year at that portfolio value, before other applicable costs. The actual fee may change when the portfolio value changes.
Hourly fees. You pay for the time spent on your financial questions or plan. This can suit an owner who needs help with a limited number of decisions rather than ongoing investment management.
Flat or project fees. The advisor charges an agreed amount for a defined service, such as creating a financial plan or reviewing retirement options. Ask what the plan includes and whether later changes cost extra.
Subscription or retainer fees. You pay a recurring amount for an agreed level of planning or access. Confirm how often meetings occur, which services are included, and whether investment management is charged separately.
Commissions or other compensation. Some professionals receive commissions when clients purchase certain financial products. This can create incentives that deserve careful review. Commission-based compensation does not automatically establish that a recommendation is unsuitable, but you should understand how the professional is paid.
How to compare the real cost
Do not choose an advisor using the headline fee alone. Ask for the total expected cost for the first year, the ongoing annual cost, and any additional product or investment charges.
For example, an hourly planner may charge less for a one-time review, while another advisor may offer continuing meetings and investment management for a larger ongoing fee. Neither option is automatically better. The right choice depends on which services you need.
The SEC’s guidance on investment advisers recommends reviewing fees, compensation, services, conflicts of interest, and the agreement before engaging an advisor.
How to Choose and Check a Financial Advisor
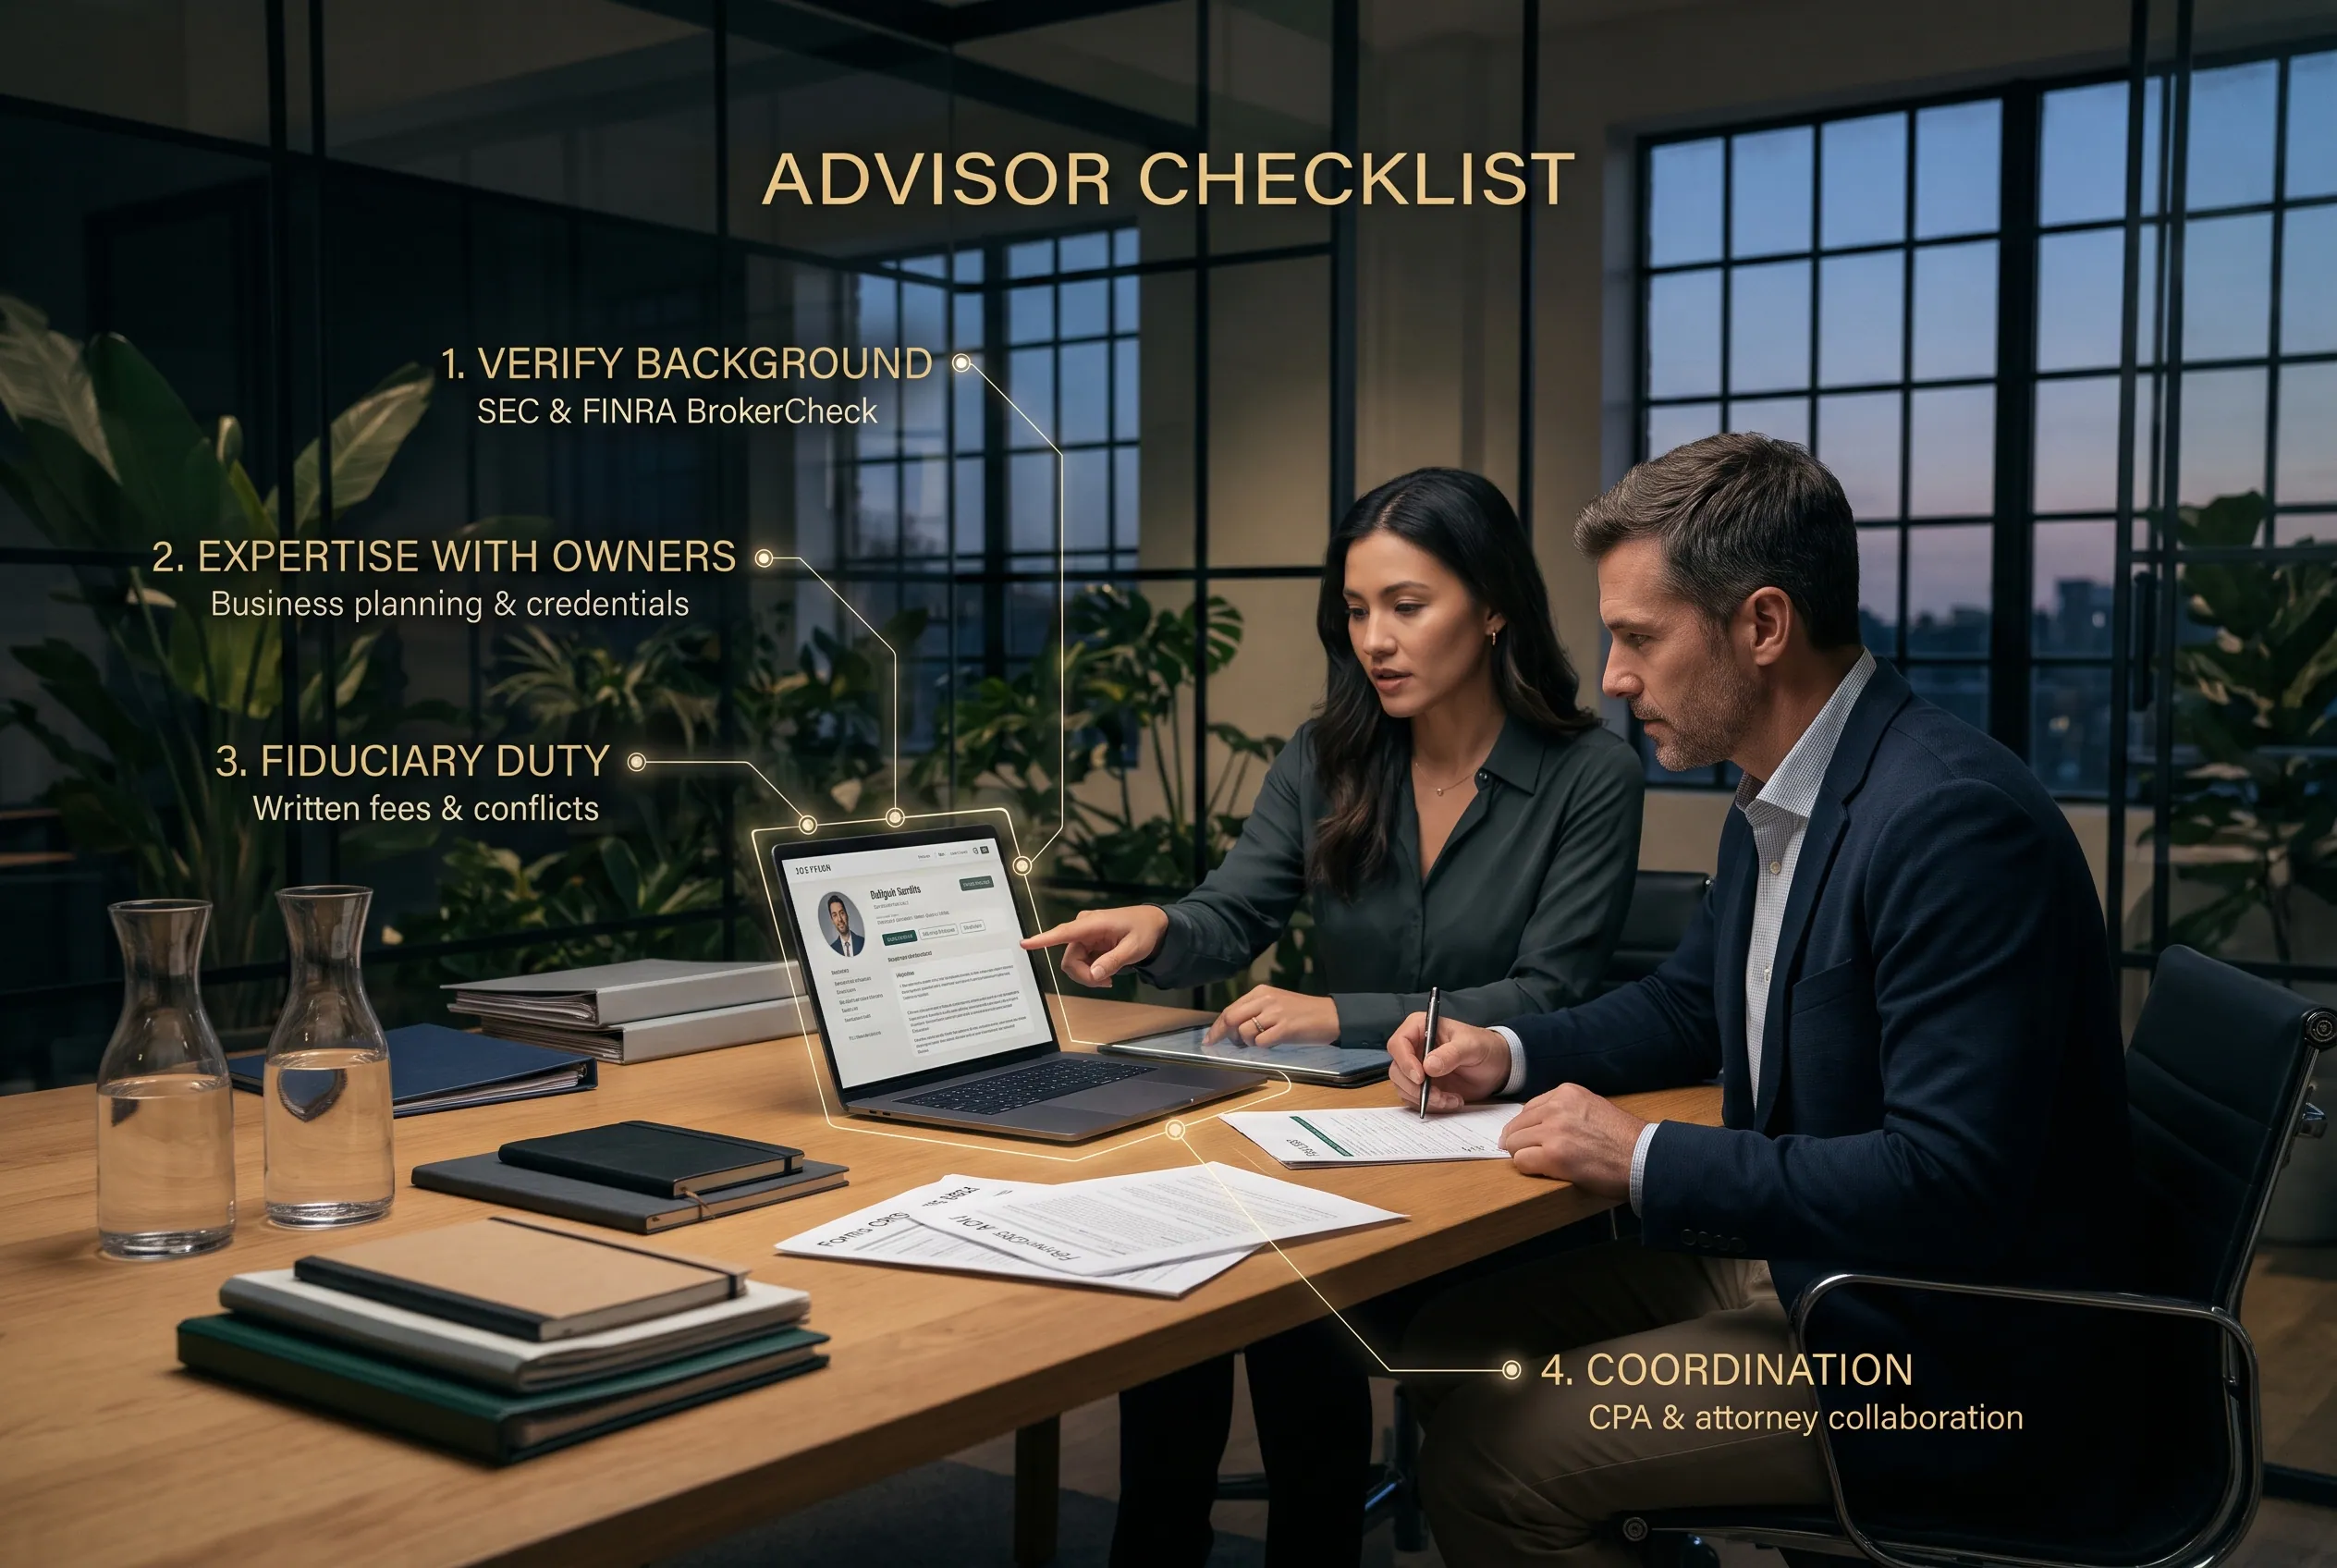 A good fit requires more than a friendly first meeting. Check the person’s relevant experience, legal registration where applicable, compensation, and willingness to explain their responsibilities.
1. Verify the advisor’s background
In the United States, the correct check depends on the professional’s role and the services offered. Investment advisers may be registered with the SEC or a state securities regulator. Broker-dealers and their associated professionals have a different regulatory framework.
Use the SEC’s Investor.gov tools for checking an investment professional to find applicable registration and background information. You can also use FINRA BrokerCheck to research brokers and brokerage firms.
When relevant, review Form CRS, a short relationship summary that explains services, fees, conflicts, standards of conduct, and reportable disciplinary history. Review Form ADV, which provides more detailed information about an investment adviser’s business practices, compensation, conflicts, and disciplinary matters.
Check both the individual and the firm when possible. Registration is an important screening step, but it does not guarantee good advice, investment performance, or suitability for your needs.
2. Check experience with business owners
Ask whether the advisor regularly works with people who have similar planning needs. Relevant experience may include self-employed retirement plans, owner compensation, concentrated business wealth, or succession planning.
You do not need an advisor who has worked in your exact industry, but they should understand the financial decisions you face or be able to explain how they will handle unfamiliar issues.
Also check professional designations or credentials the advisor claims. Ask what they mean, whether they apply to the services you need, and where you can verify them. Do not assume that a title alone proves expertise in business finance or tax planning.
3. Understand fiduciary duties and conflicts
A fiduciary has a duty to act in another person’s best interests within the relationship covered by that duty. However, the legal standards that apply to investment advisers and broker-dealers are not identical in every respect. The title “financial advisor” alone does not establish that the same duty applies to every service.
Ask the advisor to explain, in writing, which duties apply to your relationship and how they receive compensation. Request clear answers about commissions, referral payments, affiliated products, and other potential conflicts.
4. Check whether the advisor works with your other professionals
Business owners often need several types of support. An advisor who can coordinate appropriately with your CPA and attorney may help reduce gaps between financial planning, tax work, and legal arrangements.
You should still understand who is responsible for each task. Agreeing to coordinate does not automatically mean the advisor will prepare your tax returns, draft legal documents, or manage your business operations.
Questions to Ask Before Hiring
Before signing an agreement, prepare questions that reveal what you will receive, what it will cost, and how the relationship will work.
- What services will you provide? Ask for a written description of what is included and excluded.
- How do you get paid? Request the fee schedule and an explanation of any commissions, referral payments, or additional investment expenses.
- What experience do you have with business owners? Ask for an explanation of how your planning needs fit their services.
- What duties apply to our relationship? Ask for the relevant disclosures and a plain-language explanation of conflicts.
- Will you coordinate with my CPA or attorney? Clarify who will handle tax, accounting, investment, and legal tasks.
- How often will we meet? Confirm the expected meetings, reviews, communication methods, and follow-up.
- How can I end the relationship? Check cancellation terms, notice requirements, fees, and what happens to managed assets or unfinished work.
You can request a sample planning process or a written proposal before committing. Compare at least two suitable providers when practical, using the same questions and expected service needs.
Common Mistakes Business Owners Should Avoid
Hiring an advisor before defining the problem. If you need help organizing transactions or predicting when bills will come due, investment advice may not solve the immediate issue. Identify the main task first.
Comparing fees without comparing services. A one-time plan and ongoing investment management may include very different work. Compare the total cost and the work covered.
Assuming the advisor handles everything. Tax returns, bookkeeping, legal agreements, and business operations may require other professionals. Confirm who is responsible for each task.
Leaving most of your wealth tied to the business without a plan. Reinvesting can support growth, but relying heavily on one business can increase your financial risk. Consider personal savings, retirement planning, and the effect of a possible business downturn.
Waiting too long to plan a sale or retirement. An exit can involve valuation, legal structure, taxes, buyer discussions, and personal retirement needs. Starting earlier gives you more time to compare options, although it cannot guarantee a sale or a specific price.
Believing promises of guaranteed results. No advisor can guarantee investment returns, tax savings, business growth, or a successful sale merely by offering a plan. Be cautious when someone promises outcomes without explaining the risks and conditions.
Frequently Asked Questions
How much does a business financial advisor cost?
Costs depend on the services and payment method. Published October 2026 fee data from fee-only financial planning firms reported a median hourly rate of $295, a median one-time plan fee of $4,950, and a median monthly subscription of $450. These figures are benchmarks, not quotes for every business-owner advisor. Ask providers for a written estimate based on the work you need.
What does a financial advisor do for business owners?
A financial advisor may help coordinate business and personal financial goals, plan retirement savings, review investments, identify financial risks, and prepare for a future sale or ownership transfer. Services vary by professional. Business accounting, tax preparation, and legal work may still require a CPA, accountant, or attorney.
Is $100,000 enough to work with a financial advisor?
It can be, depending on the advisor and the service. Some professionals have investment minimums, while others offer hourly planning, one-time plans, or subscriptions that do not depend on managing a large portfolio. Ask about minimums and fees before sharing extensive personal financial information or agreeing to an engagement.
Can ChatGPT be used as a financial advisor?
ChatGPT can help explain financial terms, organize questions, compare general fee structures, and prepare for a meeting with a professional. It cannot replace the full review of your records, circumstances, and applicable rules that a qualified professional may provide. Verify current tax, legal, and investment information with authoritative sources, and seek appropriate professional help before making major financial commitments.
A Practical First Step
Before searching for a financial advisor for business owners, write down your main goal. You may need help with retirement savings, personal wealth, business cash flow, investment decisions, risk planning, or preparing for a sale.
Then decide which professional can address that need, compare the total cost of suitable services, and verify the person’s background before signing an agreement. If you already have a CPA or accountant, start by asking which planning needs they can handle and where another professional would add value.
The right choice is not necessarily the most expensive advisor or the one who offers the most services. It is the professional whose work, fees, experience, and responsibilities fit your actual needs and who helps you make informed decisions without promising results no one can guarantee.
Disclaimer
Financial circumstances, product terms, professional services, and applicable laws vary, so outcomes are not guaranteed. This article provides general financial education, not personalized financial, investment, legal, or tax advice; consult an appropriately qualified professional when your specific situation requires it.


