
If you have seen the term RIA while researching investments or looking for a financial adviser, you may wonder what it means. In U.S. finance, RIA stands for Registered Investment Adviser. It commonly refers to a firm registered with the Securities and Exchange Commission (SEC) or a state securities regulator to provide investment advisory services.
An RIA can help clients choose investments, manage portfolios, and plan for financial goals, depending on the services it offers. Investment advisers have a fiduciary duty, meaning they must act in their clients’ best interests within the advisory relationship. However, registration does not guarantee good advice, investment profits, or freedom from conflicts of interest.
Understanding what an RIA does can help you decide whether professional investment advice fits your needs. You will also learn how RIAs differ from retirement accounts and brokers, how advisory fees work, and how to check an adviser before hiring one.
Direct Answer
RIA stands for Registered Investment Adviser in the United States. It refers to a firm or qualifying individual registered with the SEC or a state securities regulator to provide investment advice, subject to applicable rules.
Experience
Before hiring an RIA, check the firm and individual through the official Investment Adviser Public Disclosure database. Review Form ADV to understand the services, fees, and conflicts disclosed by the firm; registration does not guarantee investment success.
What Does an RIA Actually Do?
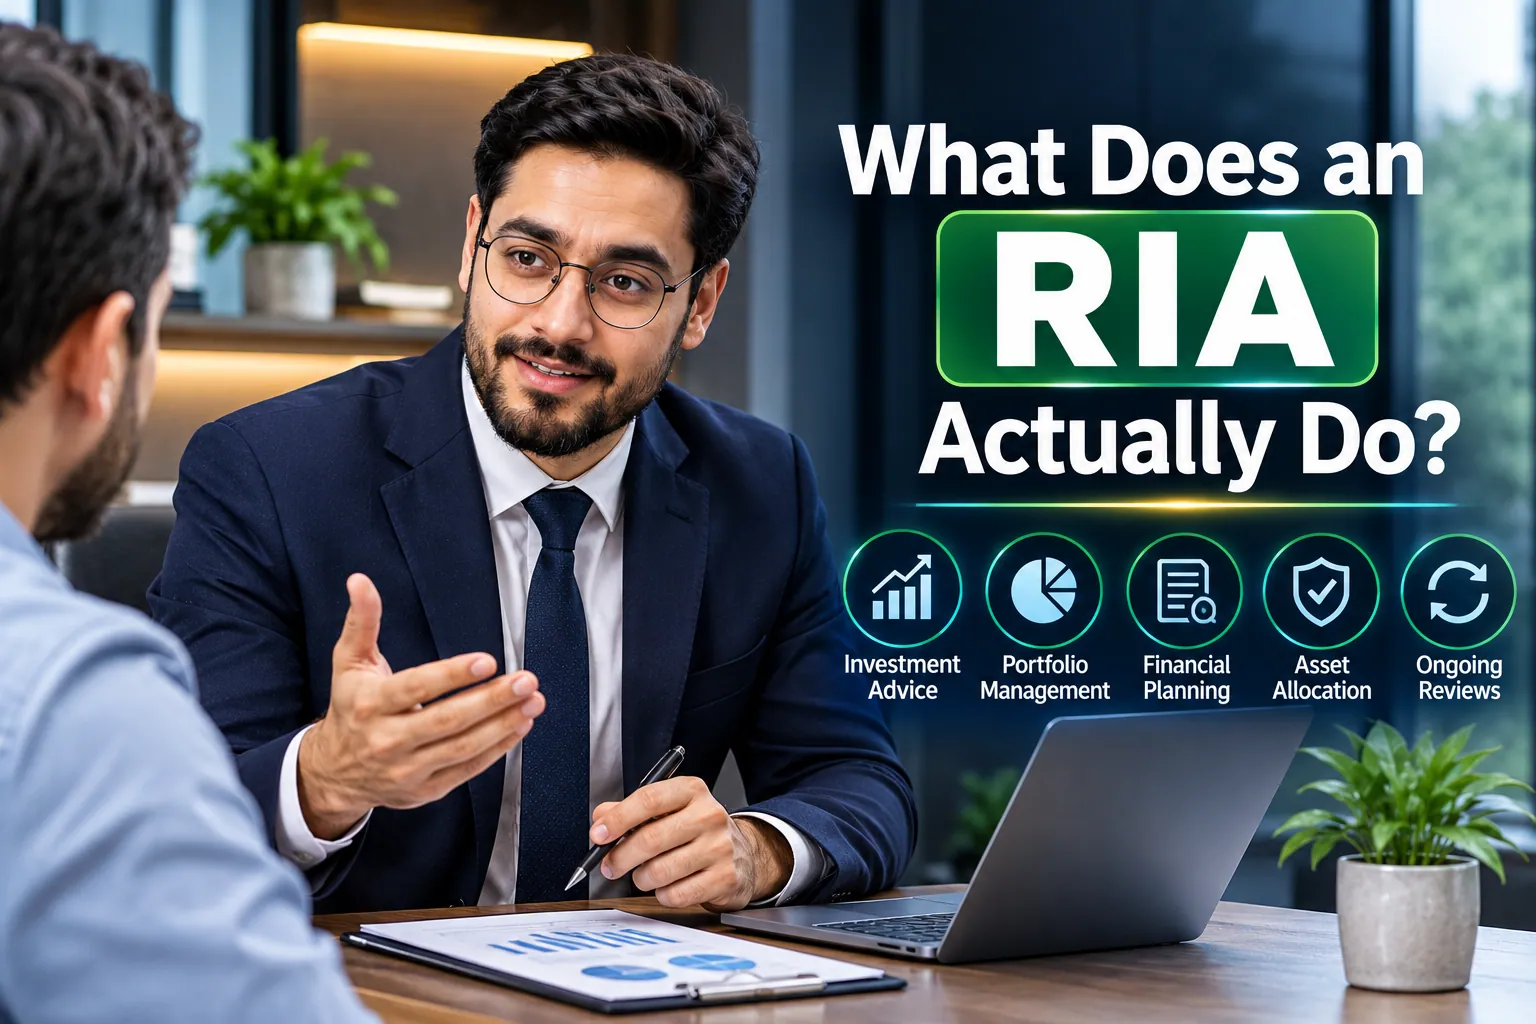 An RIA provides investment advice in exchange for compensation. It may operate as a small advisory firm, a larger financial company, or an individual advisory business. The exact services depend on the firm’s business model and its agreement with each client.
According to Investor.gov’s guide to investment advisers, advisers typically provide guidance about buying, selling, or holding investments. They may also monitor portfolios and offer financial planning.
Common services include:
- Investment selection: Helping clients understand stocks, bonds, mutual funds, exchange-traded funds (ETFs), and other investments.
- Portfolio management: Managing a collection of investments based on an agreed strategy and the client’s goals.
- Financial planning: Helping clients organize their finances around goals such as retirement, education, or other major expenses.
- Asset allocation: Deciding how to divide investments among different asset types.
- Ongoing reviews: Reviewing a portfolio or financial plan at an agreed frequency and making changes when appropriate.
Not every RIA provides all these services. One firm might manage investments but offer little broader financial planning. Another might provide a detailed financial plan without taking control of the client’s investment account.
Before working with an RIA, ask exactly what you will receive. Find out whether the adviser will manage your investments, make recommendations for you to carry out, prepare a financial plan, or provide a combination of services.
Also, understand who holds your money and how you access it. Hiring an investment adviser does not automatically mean the adviser personally holds your assets or handles every transaction.
RIA vs. IAR: What Is the Difference?
RIA and IAR describe related but different roles.
RIA usually refers to a Registered Investment Adviser firm or advisory business. IAR stands for Investment Adviser Representative, an individual who provides advisory services on behalf of an investment adviser, subject to applicable registration requirements.
Think of the difference this way: the RIA is the advisory business, while the IAR is the person you may speak with about your investments.
An IAR may discuss your financial goals, recommend investments, explain a portfolio strategy, or help implement an agreed plan. The work performed depends on the person’s responsibilities and the firm’s services.
Consider a hypothetical example. You contact an investment advisory firm to discuss your retirement portfolio. The firm is registered as an investment adviser, and an individual representative meets with you to review your goals. You are dealing with the firm and the individual who delivers its advice.
When checking an adviser, look up both the firm and the individual professional. Their registration status, employment history, and disclosure records can provide useful information about their background.
The Investment Adviser Public Disclosure (IAPD) database can help you find these records. Registration requirements for individual representatives can vary by state.
RIA vs. IRA: Adviser or Retirement Account?
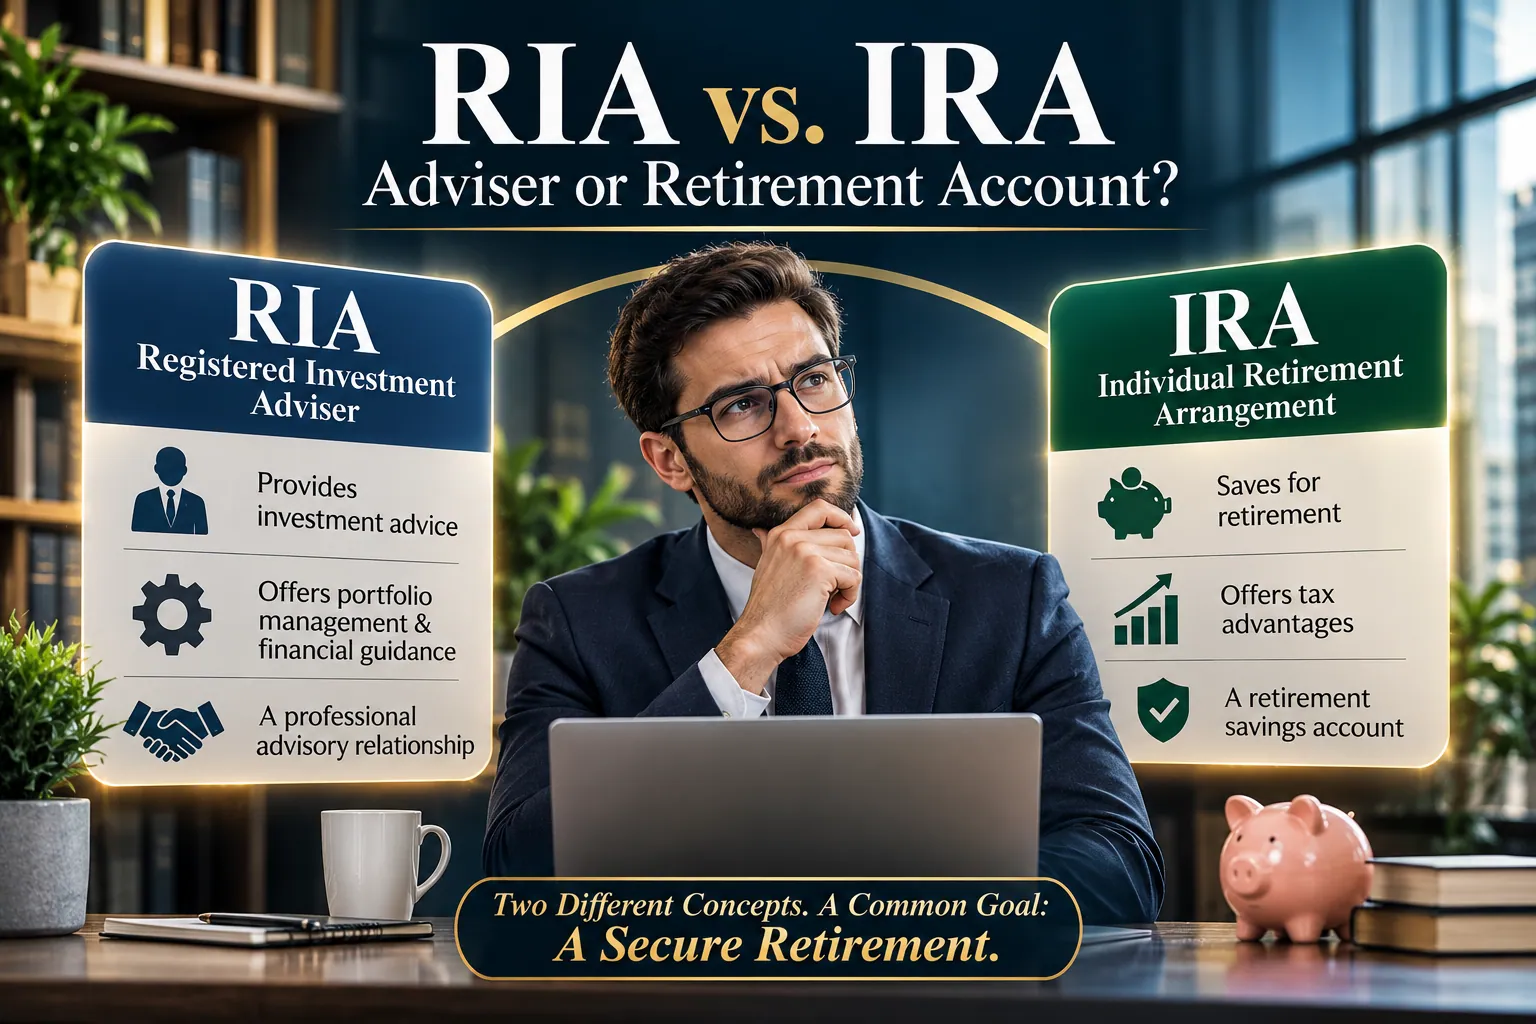 RIA and IRA look similar, but they refer to completely different things.
An RIA provides investment advice. An IRA, or Individual Retirement Arrangement, is a tax-advantaged arrangement used to save for retirement.
The Internal Revenue Service (IRS) explains the rules and types of IRAs, including Traditional and Roth IRAs.
| Feature | RIA | IRA |
| Full name | Registered Investment Adviser | Individual Retirement Arrangement |
| Main purpose | Providing investment advice or related services | Saving for retirement under applicable tax rules |
| What it is | An advisory firm or registered investment adviser | A retirement savings arrangement or account |
| How it fits into investing | Provides advice or portfolio management | Holds eligible investments for retirement |
| Main costs or rules | Advisory fees, agreement terms, and registration rules | Contribution, withdrawal, investment, and tax rules |
You can have an IRA and use an RIA at the same time. For example, you might hold investments in a Roth IRA while paying an investment adviser to help manage your retirement portfolio.
You do not need to hire an RIA simply because you have an IRA. Many people manage their own retirement accounts, while others seek professional help with investment selection, tax-aware planning, or more complex financial decisions.
The important distinction is that an IRA is the retirement savings arrangement, while an RIA is a professional advisory relationship. They are not competing products that serve the same purpose.
RIA vs. Broker-Dealer: How Are They Different?
An RIA and a broker-dealer can both help people invest, but their services, compensation, and legal duties may differ.
A broker-dealer buys and sells securities for customers, for its own account, or both. A broker may execute transactions and may also make investment recommendations or provide other services, depending on the relationship.
An investment adviser typically provides advice through an advisory relationship. Some advisers also manage portfolios and monitor investments over time.
Here are the main differences:
| Feature | Investment adviser (RIA) | Broker-dealer |
| Typical service | Investment advice and, where agreed, portfolio management | Buying and selling securities and related brokerage services |
| Common payment method | Percentage of assets, hourly fees, or flat fees | Commissions, markups, and other permitted fees |
| Standard of conduct | Fiduciary duty in the advisory relationship | Regulation Best Interest applies to recommendations of securities or investment strategies to retail customers |
| Ongoing monitoring | Depends on the agreed advisory services and scope | Depends on the services and account arrangement |
| Important checks | Fees, conflicts, registration, disclosures, and service agreement | Fees, conflicts, registration, disclosures, and brokerage agreement |
These are typical patterns, not absolute rules. An investment adviser may charge different kinds of fees, and brokers may offer services beyond executing trades.
Both groups can have financial incentives that affect their recommendations. Investment advisers have fiduciary duties. Broker-dealers making covered recommendations to retail customers must comply with Regulation Best Interest, which includes obligations relating to care, disclosure, conflicts of interest, and compliance.
Some financial professionals work in both advisory and brokerage capacities. In those cases, ask which role the person is acting in, which agreement applies, how the person is paid, and what duties apply to the recommendation.
Do not choose a professional based only on the title. Compare the services you need, the total cost, and the protections relevant to the relationship.
What Does Fiduciary Duty Mean for Investors?
 A fiduciary is someone who has a legal duty to act in another person’s best interests in a particular relationship.
Investment advisers have a fiduciary duty to their clients. In practical terms, they must provide advice that meets their applicable duties of care and loyalty. They must also address conflicts of interest, including through appropriate disclosure where required.
The SEC explains these responsibilities in its Commission Interpretation Regarding the Standard of Conduct for Investment Advisers.
Why does fiduciary duty matter?
Advisers may earn money in ways that create conflicts with their clients’ interests. For example, an adviser could receive a financial benefit from recommending one product rather than another. The product might not be the most appropriate choice for every client.
A fiduciary relationship does not mean conflicts can never exist. It means the adviser must meet applicable obligations concerning those conflicts and the client’s interests. Disclosure alone should not be treated as proof that a recommendation is suitable or that every conflict has been resolved.
The SEC’s June 9, 2026, risk alert about investment adviser conflicts discussed examination findings related to economic incentives, fee disclosures, and whether advisory fees were calculated and charged accurately. The alert is staff guidance, not a new rule or evidence that every adviser has these problems.
Questions worth asking
Before signing an agreement, ask:
- Do you receive compensation from any products you recommend?
- Do you or an affiliated company have financial interests that could affect your recommendations?
- How do you handle conflicts of interest?
- How often will you review my investments?
- What services are included in the fee, and which cost extra?
Look for clear answers that match the firm’s disclosures and written agreement. If you cannot understand how the adviser gets paid or why a particular investment is being recommended, ask for an explanation before committing.
Fiduciary duty is an important protection, but it does not remove investment risk. Your portfolio can still lose value, and an adviser cannot guarantee market performance.
How Do RIA Fees Work?
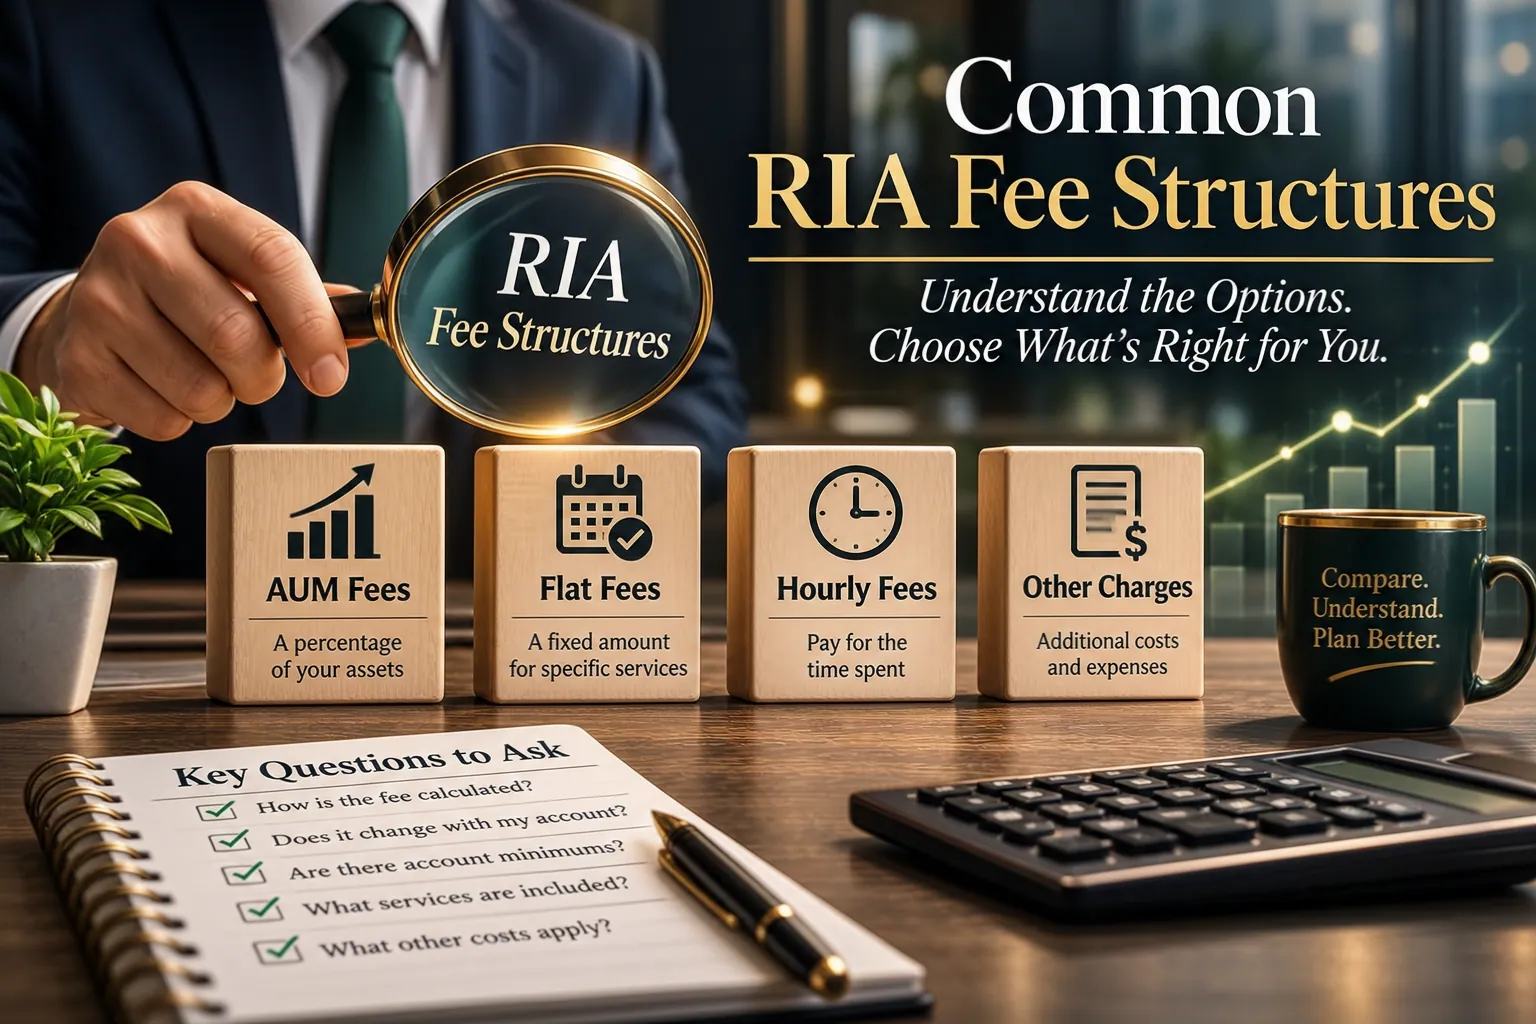
RIA fees depend on the firm’s services, its payment model, and the agreement you sign. Some advisers charge a percentage of the assets they manage. Others charge flat fees, hourly fees, or a combination of charges.
There is no single fee that applies to every RIA. The right comparison is the total cost of the services you will actually receive.
Common RIA fee structures
 1. Assets under management (AUM) fees
Assets under management, or AUM, means the investments an adviser manages or oversees for clients. An AUM-based fee is calculated as a percentage of the assets covered by the agreement.
For example, suppose an adviser charges a hypothetical annual fee of 1% on an account worth $100,000.
The simple calculation is:
$100,000 × 0.01 = $1,000 per year.
This is an illustrative calculation, not a claim that 1% is a universal or current market rate. The actual amount can change if the account value changes or if the agreement uses a different billing method, such as average or quarter-end assets.
A percentage-based fee may suit someone who wants ongoing portfolio management. However, the dollar cost can rise as the account grows, even if the level of service stays similar.
2. Flat fees
An adviser may charge a fixed amount for a specific service or period. For example, a flat fee might cover a financial plan or an agreed set of planning services.
The main advantage is that the cost may be easier to predict. The limitation is that you must understand what the fee includes, when the engagement ends, and what additional services cost.
3. Hourly fees
An hourly fee is based on the time spent providing advice or completing agreed work. It may suit someone who needs help with a defined question rather than ongoing management.
Ask how time is tracked, whether preparation and follow-up work are included, and whether the adviser provides a cost estimate.
4. Other charges
A firm may have more than one source of compensation or work with affiliated businesses that charge separate fees. The details should be disclosed and explained.
The adviser’s fee may also be separate from expenses charged by the funds you own, brokerage costs, account charges, or other investment expenses.
Investor.gov explains these issues in its guidance on investment advisers and fees. Before comparing firms, ask for the expected total cost rather than looking at the advisory fee alone.
What should you compare?
Ask each adviser to explain:
- How the fee is calculated and when it is charged.
- Whether the fee changes as your account value changes.
- Whether there are account minimums or additional charges.
- Which planning and investment services are included.
- Whether you must pay separately for fund expenses or other services.
- How you can end the relationship and whether any costs apply.
Also read the compensation and conflict disclosures in the firm’s Form ADV brochure. A written explanation makes it easier to compare two advisers offering different services.
A low fee is not automatically the best deal, and a high fee does not prove that an adviser is better. Consider the cost alongside the work being done, the clarity of the agreement, and whether the service meets your needs.
How to Check an RIA Before Hiring One
You can check an RIA before sharing sensitive financial information or signing an agreement. The process starts with official registration records, followed by a review of fees, disclosures, and the services offered.
Step 1: Search the official registration database
Visit the SEC’s Investment Adviser Public Disclosure website through Investor.gov.
Search for the firm and the individual professional you plan to work with. Confirm that the name and details match the person or business you are considering.
Review the available information about:
- Current registration status.
- The firm’s business and services.
- The individual’s professional background.
- Employment history and other registrations.
- Disciplinary events and other disclosures.
Investment advisers generally register with the SEC or state securities regulators, depending on the applicable rules and exceptions. Do not assume that every adviser must be SEC-registered. A state registration may be appropriate for a firm under the federal registration framework.
If you cannot find a record, do not automatically assume that the person is legitimate or illegitimate. Check the name and spelling, ask the professional for its exact legal name and registration details, and contact the relevant state securities regulator if needed.
Step 2: Read the firm’s Form ADV
Form ADV is a disclosure and registration filing used by investment advisers. Its public records can help you understand how the firm operates.
Investor.gov’s Form ADV guide explains the main parts:
- Part 1: Information about the firm’s business, ownership, practices, affiliations, and certain disciplinary matters.
- Part 2: A written brochure explaining services, fees, conflicts of interest, and disciplinary information.
- Part 3: The relationship summary, also known as Form CRS, which applies to SEC-registered advisers serving retail investors under the relevant requirements.
Focus on the firm’s services, fee arrangements, conflicts, and disclosed history. If something seems unclear, ask the adviser to explain it and show where the answer appears in the documents.
Step 3: Compare disclosures with the written agreement
Do not rely only on a website, sales presentation, or verbal promise. Review the actual advisory agreement.
Check what the adviser will do, how frequently the relationship will be reviewed, how much you will pay, and whether additional expenses may apply. Make sure the services described to you are consistent with the agreement and the firm’s disclosures.
If the firm offers investment management, confirm how the account will be held and who will have authority to make transactions. Understand how you will receive statements and how you can access your assets.
Step 4: Ask about conflicts and disciplinary records
A disclosure does not automatically mean an adviser is unsuitable, but it should not be ignored. Ask what happened, how it was resolved, and whether it is relevant to the services being offered.
Look at the nature of a disclosure, its date, and its context. Distinguish allegations, settled matters, and other reported events rather than treating every record as proof of the same conduct.
Before transferring money or granting account access, confirm the adviser’s identity, registration, written terms, and custody arrangements. Do not send money to an unfamiliar personal account or share passwords or security codes to speed up the process.
Registration is an essential check, not a government endorsement. The purpose of the process is to help you make an informed choice based on both the official record and the actual service being offered.
Is an RIA the Right Fit for You?
An RIA may be useful if you need ongoing investment management, help organizing a retirement strategy, or advice that connects several financial goals. Professional guidance can also be helpful when your investments or financial decisions have become too complex to manage comfortably on your own.
However, paying an adviser is not necessary for every investor.
You may prefer to manage your own investments if your needs are straightforward, you understand the choices available, and you have the time to review your portfolio and keep costs under control. You could also pay for a one-time financial plan or a limited consultation instead of ongoing management.
Consider these questions:
- What problem am I trying to solve? Be specific about whether you need investment management, a financial plan, retirement guidance, or help with a particular decision.
- How much will the service cost? Compare the advisory fee with other charges and the actual work included.
- What level of help do I need? Decide whether you need continuing support or a defined service.
- Can I explain the agreement? You should understand the services, fees, conflicts, and exit terms before signing.
- Have I checked the professional? Review official registration records and relevant disclosures for both the firm and the individual.
The goal is not to find an adviser at any cost. It is to decide whether the services justify the expense and fit your needs.
Frequently Asked Questions
1. Is it legal to operate as an RIA in the United States?
Yes. Providing investment advisory services is a lawful business activity when the firm or individual meets the applicable registration and other legal requirements or qualifies for an exemption. The rules depend on the type of adviser, the business, and the relevant jurisdiction.
For a reader considering hiring an adviser, the practical step is to check the professional’s registration and disclosures through IAPD.
2. Does SEC registration mean an RIA is government-endorsed?
No. SEC registration is not a recommendation, approval of investment performance, or guarantee that an adviser is right for you. Registration records provide useful information, but you should still review the firm’s services, fees, conflicts, and disciplinary disclosures.
3. Does hiring an RIA guarantee better investment returns?
No. An RIA may help you develop and manage an investment strategy, but markets can fall and investments can lose money. Fees also reduce the amount of your returns that you keep.
Evaluate an adviser based on the services provided, the way the strategy fits your goals, the costs involved, and the quality of the relationship—not on promises of guaranteed profits.
4. Can a financial professional work as both an investment adviser representative and a broker?
Yes. Some professionals are associated with both an investment adviser and a broker-dealer. The services offered, compensation, and applicable duties can differ depending on the capacity in which they act.
Ask which relationship applies to your account, how the professional gets paid, and which disclosures and agreements govern the recommendation. Review the firm’s records and the individual’s registration rather than relying on a general job title.
A Practical Next Step Before Hiring an RIA
Start by identifying the financial help you need. Then search for the firm and individual through IAPD, read their disclosures, and compare the written fees and services with other suitable options.
You do not need to commit immediately. A clear understanding of the adviser’s role, costs, conflicts, and terms can help you decide whether professional guidance is worth paying for.
Disclaimer
This article provides general financial education, not personalized financial, investment, legal, or tax advice. Financial needs, adviser fees, product terms, and regulatory requirements vary, and investment outcomes are not guaranteed. Consider consulting an appropriately qualified financial or tax professional when your circumstances require individual guidance.