
Buying an existing business can give you customers, equipment, employees, and an established way to earn money. But before you agree to a price, you need to understand what you are actually buying and whether the business can support its costs after the sale.
The most important questions to ask when buying a business cover its financial records, asking price, debts, customers, operations, employees, and legal obligations. Ask the seller for clear answers, then verify those answers with documents and independent checks. A seller’s promises are not a substitute for evidence.
The U.S. Small Business Administration (SBA) recommends reviewing a business’s contracts, leases, cash flow, inventory, and other important details before buying it. Use the following 43 questions to guide your seller meetings and due diligence, which means checking a business carefully before committing to the purchase.
Direct Answer
When buying a business, ask about financial records, profits, cash flow, valuation, debts, assets, customers, employees, and legal obligations. Verify the seller’s answers with documents before committing to the purchase.
Experience
Ask the seller to support important claims with financial statements, tax returns, bank records, and contracts. If the numbers do not match, request an explanation and independent review before proceeding. A missing document does not automatically mean fraud, but unresolved gaps can make a purchase too risky.
43 Questions to Ask When Buying a Business
1. Questions About the Seller and Business History
 Start by understanding why the owner wants to sell and how the business has performed. These answers can help you identify issues that need further investigation.
- Why are you selling the business?
Ask for the seller’s main reason, whether it is retirement, a career change, a new opportunity, or another concern. Compare the answer with the business’s financial history. A reasonable explanation is useful, but it does not prove the business is performing well.
- How long have you owned the business, and what changes have you made?
Ask when the current owner took over, what improvements they introduced, and which major problems they faced. This helps you separate the business’s long-term performance from changes caused by the current owner.
- How have sales and profits changed over the past several years?
Ask whether the business has grown, stayed stable, or lost ground. Request explanations for major changes, especially recent declines. Check whether rising sales also produced better profits or simply increased operating costs.
- How much does the business depend on you personally?
Find out whether customers rely on the owner, whether only the owner can perform important tasks, and who manages daily operations. A business that cannot run without its former owner may need additional staff, training, or a longer transition.
- What are the biggest risks and opportunities you see for this business?
Ask the seller to explain upcoming challenges, possible growth areas, and any changes that could affect demand. Compare these claims with customer trends, expenses, competition, and industry conditions rather than accepting optimistic forecasts without evidence.
2. Financial Questions to Ask Before Buying
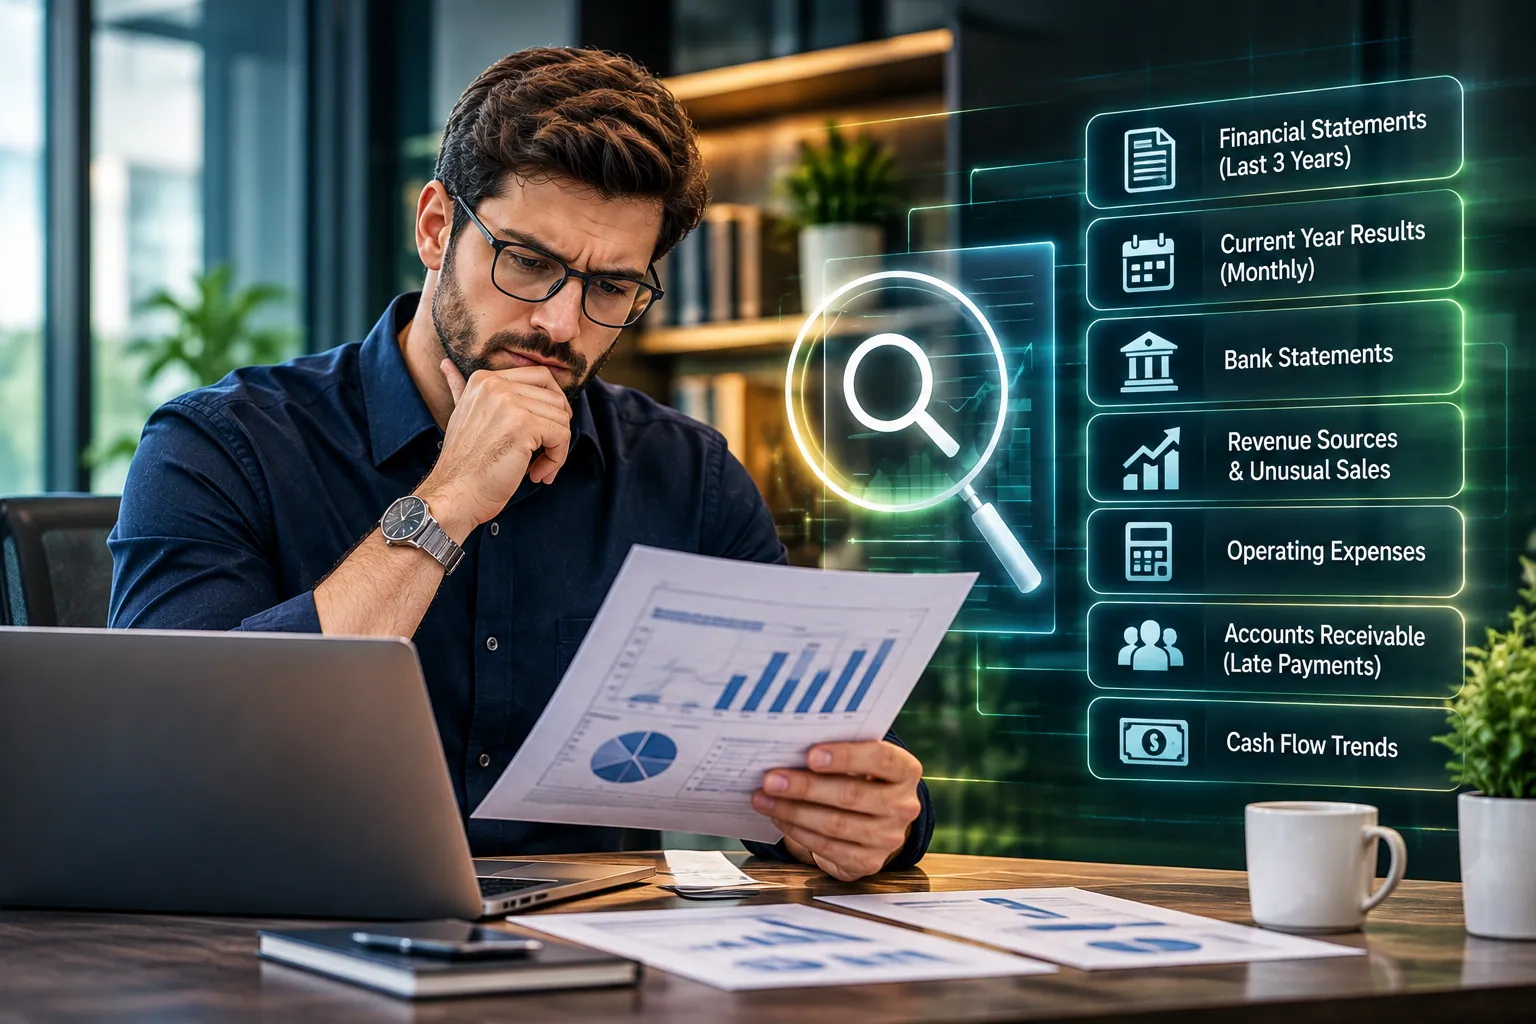
Financial records help you determine whether the business generates enough income to justify its price. Ask for several years of records and recent monthly figures, not just a summary prepared for prospective buyers.
- Can I review the last three years of financial statements and tax returns?
Request income statements, balance sheets, cash-flow statements, and business tax returns for the available years. An independent accountant can compare these records and identify differences that require explanation. Three years is a useful starting point, not a universal legal requirement.
- Can I see current year-to-date and monthly financial results?
Annual reports may hide recent problems. Ask for monthly sales, expenses, and profit figures for the current year and compare them with the same months in previous years. This can reveal seasonal changes, declining demand, or unexpected cost increases.
- Do bank statements support the revenue reported in your financial records?
Compare deposits with reported sales and ask about significant differences. Not every bank deposit is revenue, and not every sale produces an immediate deposit. Your accountant should investigate transfers, loans, refunds, cash sales, and other items that explain the differences.
- How is revenue earned, and are any sales unusual or unlikely to repeat?
Find out which products or services generate income, when customers pay, and whether recent results include one-time orders or unusual contracts. Separate repeat business from temporary income so you can judge how dependable future sales may be.
- What are the main operating expenses, and why have they changed?
Review rent, payroll, supplies, insurance, utilities, marketing, and other major costs. Ask why any expense has risen or fallen. Low expenses may reflect unpaid owner labor, deferred maintenance, or temporary savings that will not continue after the purchase.
- What owner-related expenses or other adjustments are included in the reported earnings?
Ask whether the seller has added back personal costs, one-time expenses, or the owner’s pay when calculating earnings. Request proof for every adjustment. Some costs may genuinely be unusual, while others will continue under your ownership.
- Are customers late paying their invoices, and how much money may never be collected?
If the business sells on credit, review accounts receivable, which means money customers owe. Ask which invoices are overdue, whether disputes exist, and how often debts go unpaid. Confirm how unpaid invoices will be handled in the agreement.
- How much cash does the business generate, and how does that change during the year?
Ask when cash enters and leaves the business, how seasonal demand affects the balance, and whether payroll or supplier payments become difficult during slow periods. A business can report a profit but still struggle to pay bills when cash arrives late.
3. Questions About Business Valuation and Asking Price
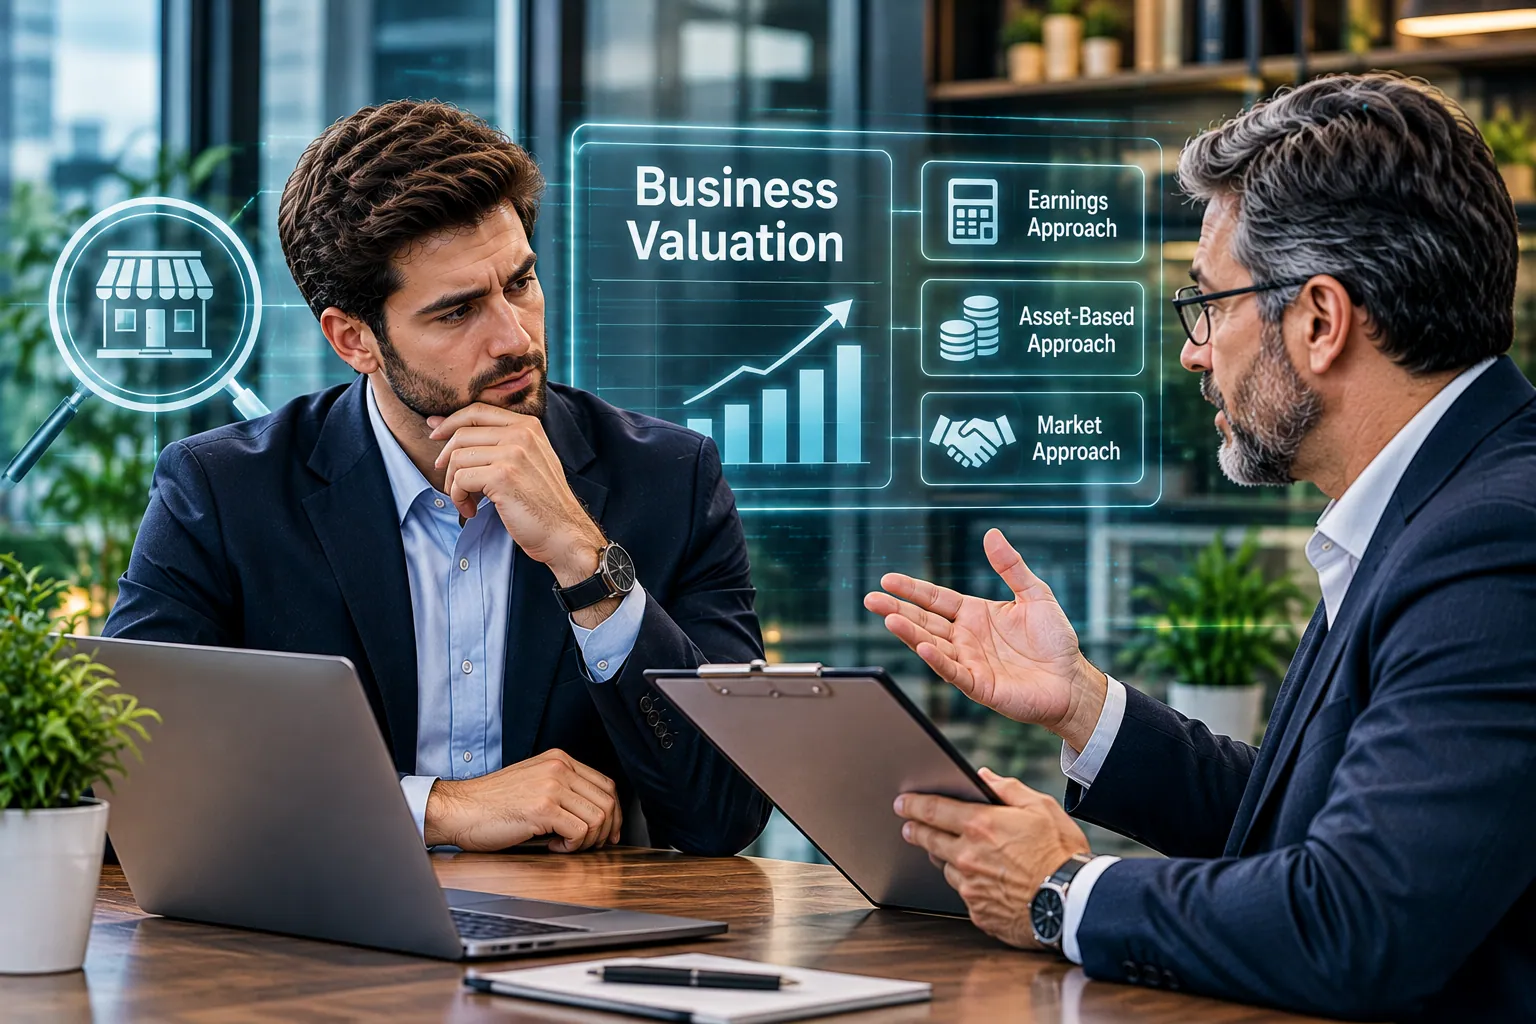 The asking price is the seller’s requested amount, not proof of what the business is worth. The SBA explains different valuation approaches in its business management guidance.
- How did you calculate the asking price?
Ask whether the seller used business earnings, asset values, comparable sales, or another method. Request the calculations and assumptions behind the price. Consider having an independent valuation professional review them when the amount is significant.
- Which earnings figure are you using to support the price?
Small businesses may be valued using net income, seller’s discretionary earnings (SDE), or earnings before interest, taxes, depreciation, and amortization (EBITDA). These measures are different. Confirm exactly what the seller’s figure includes before comparing it with another business.
- Can you provide supporting records for every adjustment to reported earnings?
A seller may claim that certain expenses will disappear after the sale. Ask for invoices, accounting entries, and other proof. If an expense will continue under your ownership, include it when estimating the business’s future financial performance.
- What comparable business sales support your asking price?
Ask which businesses were sold, when the sales occurred, and how they compare in size, industry, location, profitability, and operating risk. A business with similar sales may have very different earnings or obligations, so comparisons need context.
- What exactly is included in the asking price?
Clarify whether the price includes inventory, equipment, intellectual property, customer relationships, real estate, and working capital. Also identify cash, debts, and other items that are excluded or handled separately. This prevents confusion about the actual cost of the transaction.
4. Questions About Assets, Debts, and Working Capital
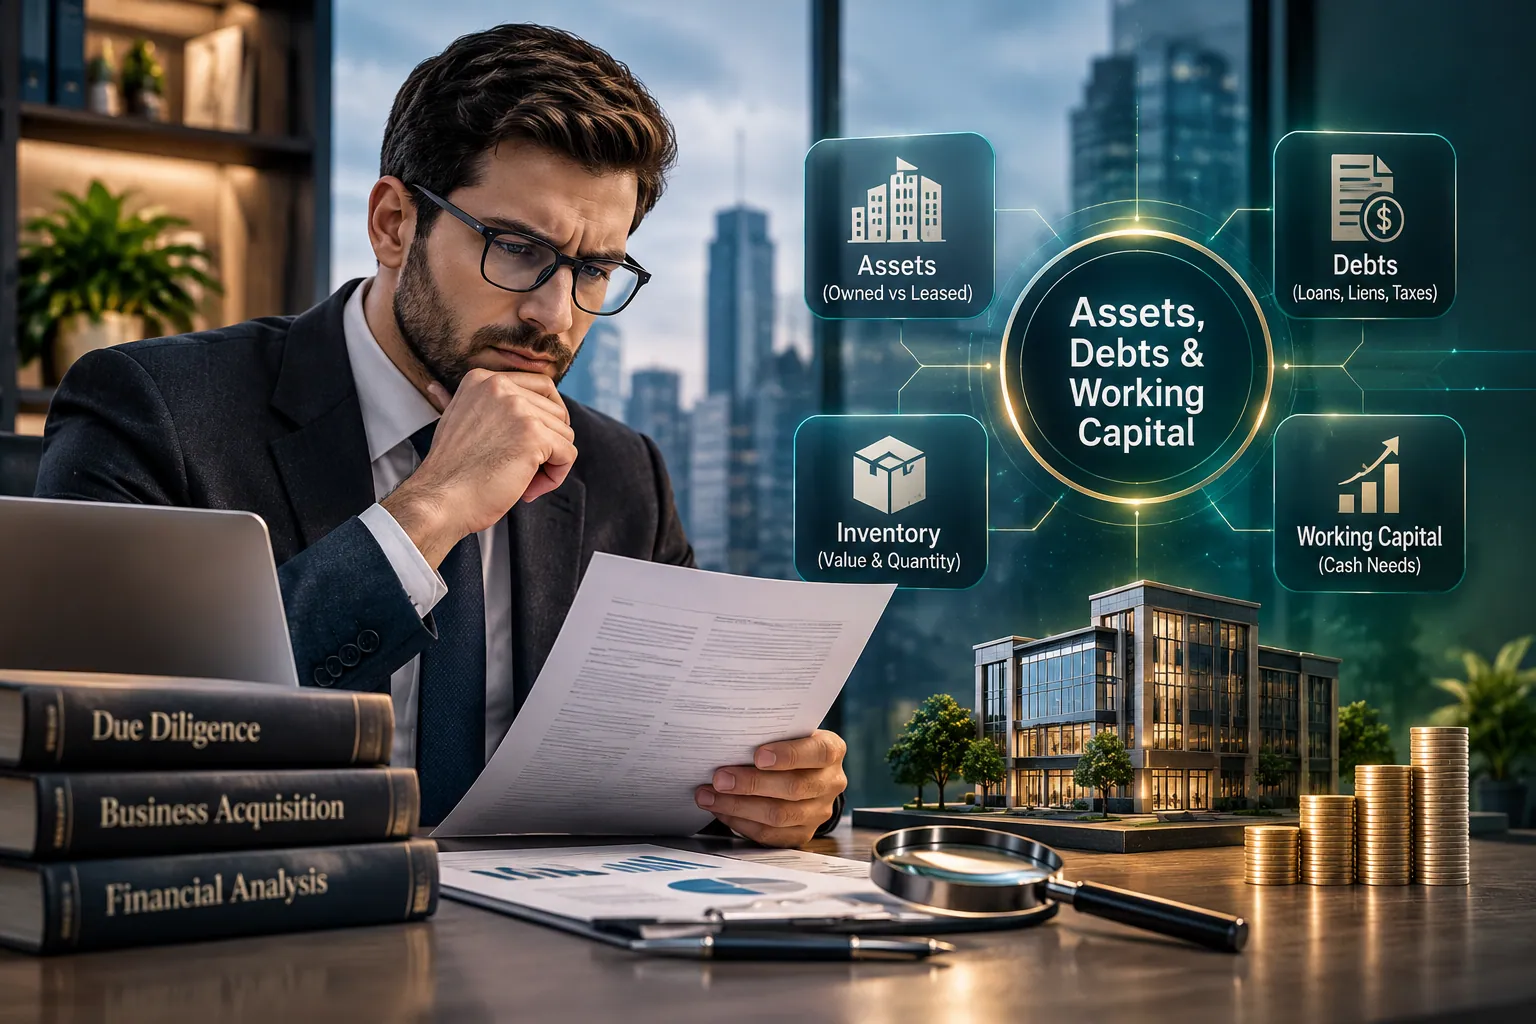
A buyer needs to know which assets will transfer and which obligations may affect the deal. The purchase price is only one part of the financial commitment.
- What loans, credit lines, liens, or other secured debts affect the business?
Request a complete debt schedule, including balances, payment terms, and security interests. A lien is a legal claim against property that can affect its transfer. Have the appropriate professional verify which debts must be paid or released at closing.
- Does the business owe money for taxes, payroll, suppliers, or other bills?
Ask about unpaid invoices, tax balances, employee payments, legal claims, and overdue rent. Compare the answers with accounting records and available official notices. Do not assume these obligations disappear automatically when ownership changes.
- Which assets does the business own, and which does it rent or lease?
Request an asset list covering equipment, vehicles, computers, furniture, software, and other important property. Check ownership documents, lease agreements, and any financing arrangements. Confirm that the seller has the right to transfer the assets included in the agreement.
- What condition is the equipment in, and what repairs or replacements will be needed?
Inspect important equipment and ask about its age, maintenance, breakdowns, and repair history. Obtain independent inspections when appropriate. Equipment that works today may still require expensive repairs soon, which can change how much cash you need after closing.
- How much inventory is included, and how is its value determined?
Ask for a current inventory list and explain how damaged, expired, outdated, or slow-moving items are valued. Compare the records with a physical count where practical. Inventory on a financial statement may not be worth its recorded amount.
- How much working capital will I need after the purchase?
Working capital is the money available to support daily operations. Estimate the cash needed for payroll, rent, inventory, supplier payments, repairs, and delayed customer payments. Ask the seller how much cash the business normally needs during both busy and slow periods.
5. Questions About Customers, Suppliers, and Competition
 A business may appear profitable because it has a few strong relationships. Your next task is to find out whether those relationships and sources of demand are likely to continue after the sale.
- Who are the largest customers, and how much revenue comes from each?
Request customer sales figures for the past several years, using appropriate confidentiality protections. If a small number of customers account for much of the revenue, investigate whether they are likely to stay after the ownership change.
- How much business comes from repeat customers, and how often do customers leave?
Ask about repeat purchases, contract renewals, cancellations, refunds, and customer complaints. Review available records rather than relying only on the seller’s description. A reliable base of returning customers may be valuable, but future purchases are never guaranteed.
- Will customers continue working with the business after you take over?
Ask why customers choose the company and whether their relationships depend on the current owner. Identify important introductions or retention steps needed during the transition. Where appropriate, your agreement should address how customer relationships will be supported without violating privacy or contract rules.
- Who are the main suppliers, and will their contracts continue after the sale?
Ask whether the business relies heavily on one supplier, whether prices or payment terms may change, and whether contracts require consent when ownership changes. Verify whether replacement suppliers are available if an important relationship cannot continue.
- How strong is demand for the business, and who are its main competitors?
Look at customer reviews, pricing, local demand, competitor offerings, and changes in the industry. Ask what makes customers choose this business over other options. Be cautious when a valuation assumes future growth without a clear reason to expect it.
6. Questions About Daily Operations and Employees
 A business needs people, systems, and reliable processes to keep operating. Determine whether these can transfer smoothly to a new owner.
- How does the business operate on a normal day?
Ask who handles sales, purchasing, customer service, scheduling, bookkeeping, and quality control. Request written procedures where available. You need to understand which tasks you must perform yourself and which require existing employees or new hires.
- Which employees are essential, and are they likely to stay?
Identify employees who manage customers, specialized work, or key systems. Ask what roles they perform and whether they have indicated a willingness to remain. Treat retention as uncertain until the relevant arrangements have been confirmed.
- What are the payroll costs, employee benefits, and outstanding staff issues?
Review wages, bonuses, benefits, leave balances, turnover, and any known employment disputes. Ask whether important pay or benefit changes are expected. Have an appropriate professional check obligations that may apply to the transaction and the employees affected.
- What software, systems, and digital assets does the business use?
Make a list of accounting systems, websites, domain names, customer databases, online accounts, and operating software. Check ownership, license terms, access rights, recurring fees, and transfer restrictions. Do not assume that a software subscription or digital account can automatically be transferred.
- What maintenance, technical knowledge, or other work keeps the business running?
Ask which systems need regular attention, whether maintenance has been delayed, and who understands specialized processes. Identify undocumented knowledge that only the seller or one employee possesses. A smooth handover may require written instructions and practical training.
7. Legal, Tax, Lease, and Licensing Questions
 Legal requirements depend on the business type, transaction structure, and location. General guidance can identify issues, but it cannot replace a review of the actual agreements and applicable law.
- Are there any current or threatened lawsuits, claims, audits, or regulatory investigations?
Ask about pending disputes, past claims that remain unresolved, insurance issues, and government inquiries. Have a transaction lawyer review relevant records and assess their possible effect on the deal. An unanswered question should not be treated as proof that no problem exists.
- Are all required tax returns filed, and are any taxes unpaid or disputed?
Request relevant tax records and ask about notices, payment plans, audits, and outstanding balances. An accountant or tax professional can identify issues that deserve closer review. The buyer should understand how tax responsibilities are treated under the proposed transaction and applicable law.
- Which contracts require approval before ownership changes?
Review important customer, supplier, licensing, service, and financing agreements. Some may allow transfer, while others may require consent or give the other party a termination right. Ask your lawyer to identify the agreements that could affect the sale.
- Can the property lease transfer to me, and could the terms change?
If the business rents its premises, read the existing lease and ask the landlord about assignment, renewal, rent changes, and required approvals. A location-dependent business may lose much of its value if it cannot stay at its current site on workable terms.
- Which licenses, permits, and certifications are required after the purchase?
Identify the federal, state, county, and city requirements relevant to the industry and location. Check whether approvals transfer or whether the new owner must apply again. Verify the requirements with the appropriate authorities before relying on the seller’s assurances.
- Is this an asset purchase or a stock or equity purchase, and what are the tax consequences?
In an asset purchase, the buyer acquires specified business assets. In a stock or equity purchase, the buyer acquires ownership interests in the legal entity. The consequences for contracts, liabilities, and taxes can differ substantially.
For some qualifying asset acquisitions, the buyer and seller must report the allocation of the purchase price using IRS Form 8594. Whether that requirement applies depends on the transaction. Have a lawyer and tax professional review the proposed structure before signing.
8. Questions About Transition and Closing the Deal
 Once the main risks are understood, focus on transferring the business and documenting the remaining conditions.
- How much training and transition support will you provide after the sale?
Agree on the length of the transition, training tasks, availability, and any additional fee. Ask whether the seller will introduce important customers and suppliers or explain specialized processes. Put the agreed arrangements in writing.
- What conditions must be satisfied before closing?
List outstanding documents, inspections, financing approvals, landlord consent, contract assignments, and required permits. Make sure the agreement explains which conditions must be met and what happens if they are not. Do not treat an expected approval as a completed one.
- What protections, promises, and payment terms will the purchase agreement include?
Ask how the agreement handles inaccurate seller statements, undisclosed liabilities, disputes, and problems discovered after closing. If the seller offers financing, confirm the repayment terms and conditions. Have a qualified transaction lawyer review the final agreement before you commit.
How to Verify the Seller’s Answers
Asking the right questions is only the first step. You also need a repeatable way to confirm the information and decide what the findings mean for your purchase.
1. Build a document request list
Organize your requests into financial, legal, operational, employee, and asset records. Begin with financial statements, tax returns, bank records, debt schedules, important contracts, leases, and inventory information.
Keep track of what you have received and what remains missing. If the seller cannot provide a record, ask why and consider what other evidence could support the same fact.
2. Compare different records
Look for consistency between the seller’s statements and the available documents.
For example, if a seller reports strong sales growth, compare monthly financial reports with bank deposits, invoices, and tax filings. Timing differences can have legitimate explanations, but important gaps need to be resolved before you rely on the figures.
The SCORE checklist for buying an existing business offers additional prompts about financial statements, taxes, debts, customers, contracts, suppliers, and employees.
3. Check the business independently
Arrange suitable inspections of equipment and property. Verify important ownership records, confirm relevant licenses with the proper authorities, and review contracts that might not transfer automatically.
An accountant can examine earnings, expenses, debt, and working capital. A qualified transaction lawyer can review the purchase agreement and identify legal risks. Choose help based on the size, complexity, and nature of the deal.
4. Record every unresolved issue
Use a simple table to connect each concern with evidence and a next step.
| Issue | Evidence to request | Next action |
| Reported profit seems too high | Tax returns, bank statements, expense details | Request an accountant’s review |
| Equipment ownership is unclear | Purchase records, finance agreements, asset list | Verify ownership and any liens |
| Lease transfer is uncertain | Current lease and landlord’s written response | Resolve approval before closing |
| Large customer may leave | Contract terms and customer retention information | Assess the effect on future revenue |
The goal is not to find a perfect business with no risks. It is to understand the risks, determine their financial effect, and decide whether the proposed deal still makes sense.
Red Flags That Should Make You Pause
Some answers should lead to more investigation rather than an immediate purchase decision.
Watch for these warning signs:
- Financial records do not agree. Sales, tax returns, bank statements, and accounting reports show differences that the seller cannot explain.
- The seller refuses important document requests. You cannot adequately assess a material claim without supporting information.
- The price relies on uncertain future growth. The seller expects major growth but cannot provide credible reasons or evidence.
- Important debts or obligations are unclear. Existing loans, tax issues, lawsuits, or unpaid bills remain unresolved.
- The business depends heavily on one relationship. Losing a major customer, supplier, or key employee could damage revenue or operations.
- The transfer depends on approvals not yet obtained. A lease, contract, or required license may not continue after the sale.
- You are pressured to close before completing checks. You are asked to commit before reviewing important records or resolving material concerns.
One red flag does not automatically mean the seller is dishonest. But do not ignore it just because you like the business.
When a concern appears, ask for supporting evidence, obtain professional advice where needed, and estimate the financial impact. Depending on the findings, you may need to negotiate different terms, delay closing, or walk away.
What to Check Before You Finalize the Purchase
Before signing a final agreement or completing the transaction, confirm that the following points are addressed:
- The reported financial performance is supported by suitable records.
- The asking price has a reasonable and documented basis.
- Existing debts, liabilities, and excluded assets are clearly identified.
- You understand the working capital and immediate spending needs.
- The condition and ownership of important assets have been checked.
- Key customers, suppliers, employees, contracts, and leases have been reviewed.
- Required licenses, approvals, and transfer conditions have been confirmed.
- Your financing and expected repayment obligations are understood.
- The purchase agreement clearly sets out what transfers, what is excluded, and each party’s responsibilities.
- Relevant accounting, legal, and tax reviews have been completed.
Important: Before making a binding commitment, understand any deposit or financing obligations, deadlines, and conditions for withdrawing from the deal. Do not assume you can recover money or cancel an agreement simply because you later discover a problem.
Frequently Asked Questions
How much is a business worth with $1,000,000 in sales?
There is no reliable valuation based on sales alone. A business generating $1 million in annual revenue could have very different values depending on its profits, cash flow, assets, debts, industry, customer stability, and operating risks. Ask for financial records and get an appropriate valuation rather than applying an unsupported universal multiple.
What financial records should I request before buying a business?
Start with the last three years of available financial statements and tax returns, plus current year-to-date and monthly reports. Depending on the business, you may also need bank statements, debt schedules, accounts receivable and payable, inventory records, payroll information, and supporting details for unusual expenses.
Do I become responsible for the business’s existing debts?
That depends on the deal structure, the obligations involved, the purchase agreement, and applicable law. Buying specified assets is not the same as acquiring ownership of the company, but an asset purchase does not automatically eliminate every possible liability. Have a transaction lawyer identify which obligations may transfer or affect the assets.
What should I do if the seller refuses to provide financial records?
Ask which records are unavailable and whether alternative evidence can support the seller’s claims. An accountant may help identify other useful checks. If important financial information remains unverified, pause the transaction rather than treating unsupported earnings or assets as established facts.
Should I hire an accountant and lawyer before buying a business?
For a significant business purchase, both can provide useful but different reviews. An accountant can examine financial performance, earnings adjustments, debt, and working capital. A transaction lawyer can review contracts, liabilities, transfer requirements, and the purchase agreement. A tax professional may also help assess the tax treatment of the transaction.
Make Your Decision Based on Evidence, Not Promises
Buying an existing business means taking on both an opportunity and a set of responsibilities. The right questions help you understand what generates its income, what could reduce its value, and what you may need to spend after taking ownership.
Use these 43 checks to prepare for seller meetings, request records, and identify unanswered questions. Verify the important facts before negotiating final terms. If the evidence supports the price and the remaining risks are manageable, you can make your decision with a much clearer understanding of what you are buying.
Disclaimer
This article provides general financial education, not personalized financial, investment, legal, or tax advice. Business values, financial risks, legal requirements, and tax consequences vary by transaction and location, and no purchase outcome is guaranteed. Consider consulting a qualified accountant, transaction lawyer, or tax professional before completing a business purchase.