
A property trust is a legal arrangement used to hold and manage real estate, such as a house, rental property, or land. In the United States, homeowners often consider a property trust as part of an estate plan to help manage their property during their lifetime and pass it to family members after death.
A property trust may help you avoid probate, plan for future incapacity, and organize how your home passes to your beneficiaries. However, a trust does not automatically save taxes or protect your home from every creditor. You must choose an appropriate trust, transfer the property correctly, and understand the legal and financial consequences.
Whether a property trust makes sense depends on your goals, state law, property ownership, mortgage terms, and budget. Understanding these factors can help you decide whether a trust is worth the cost or whether a simpler estate-planning option may suit you better.
Direct Answer
A property trust is a legal arrangement used to hold and manage real estate. In the US, it may help with probate and incapacity planning, but benefits depend on the trust terms and proper property transfer.
Experience
Practical Finance Tip: Before paying to create a trust, check the current deed and ask how the property will be transferred into it. A signed trust document alone does not prove the house is titled in the trust, and mortgage, insurance, and state-law requirements may still apply.
What Is a Property Trust?
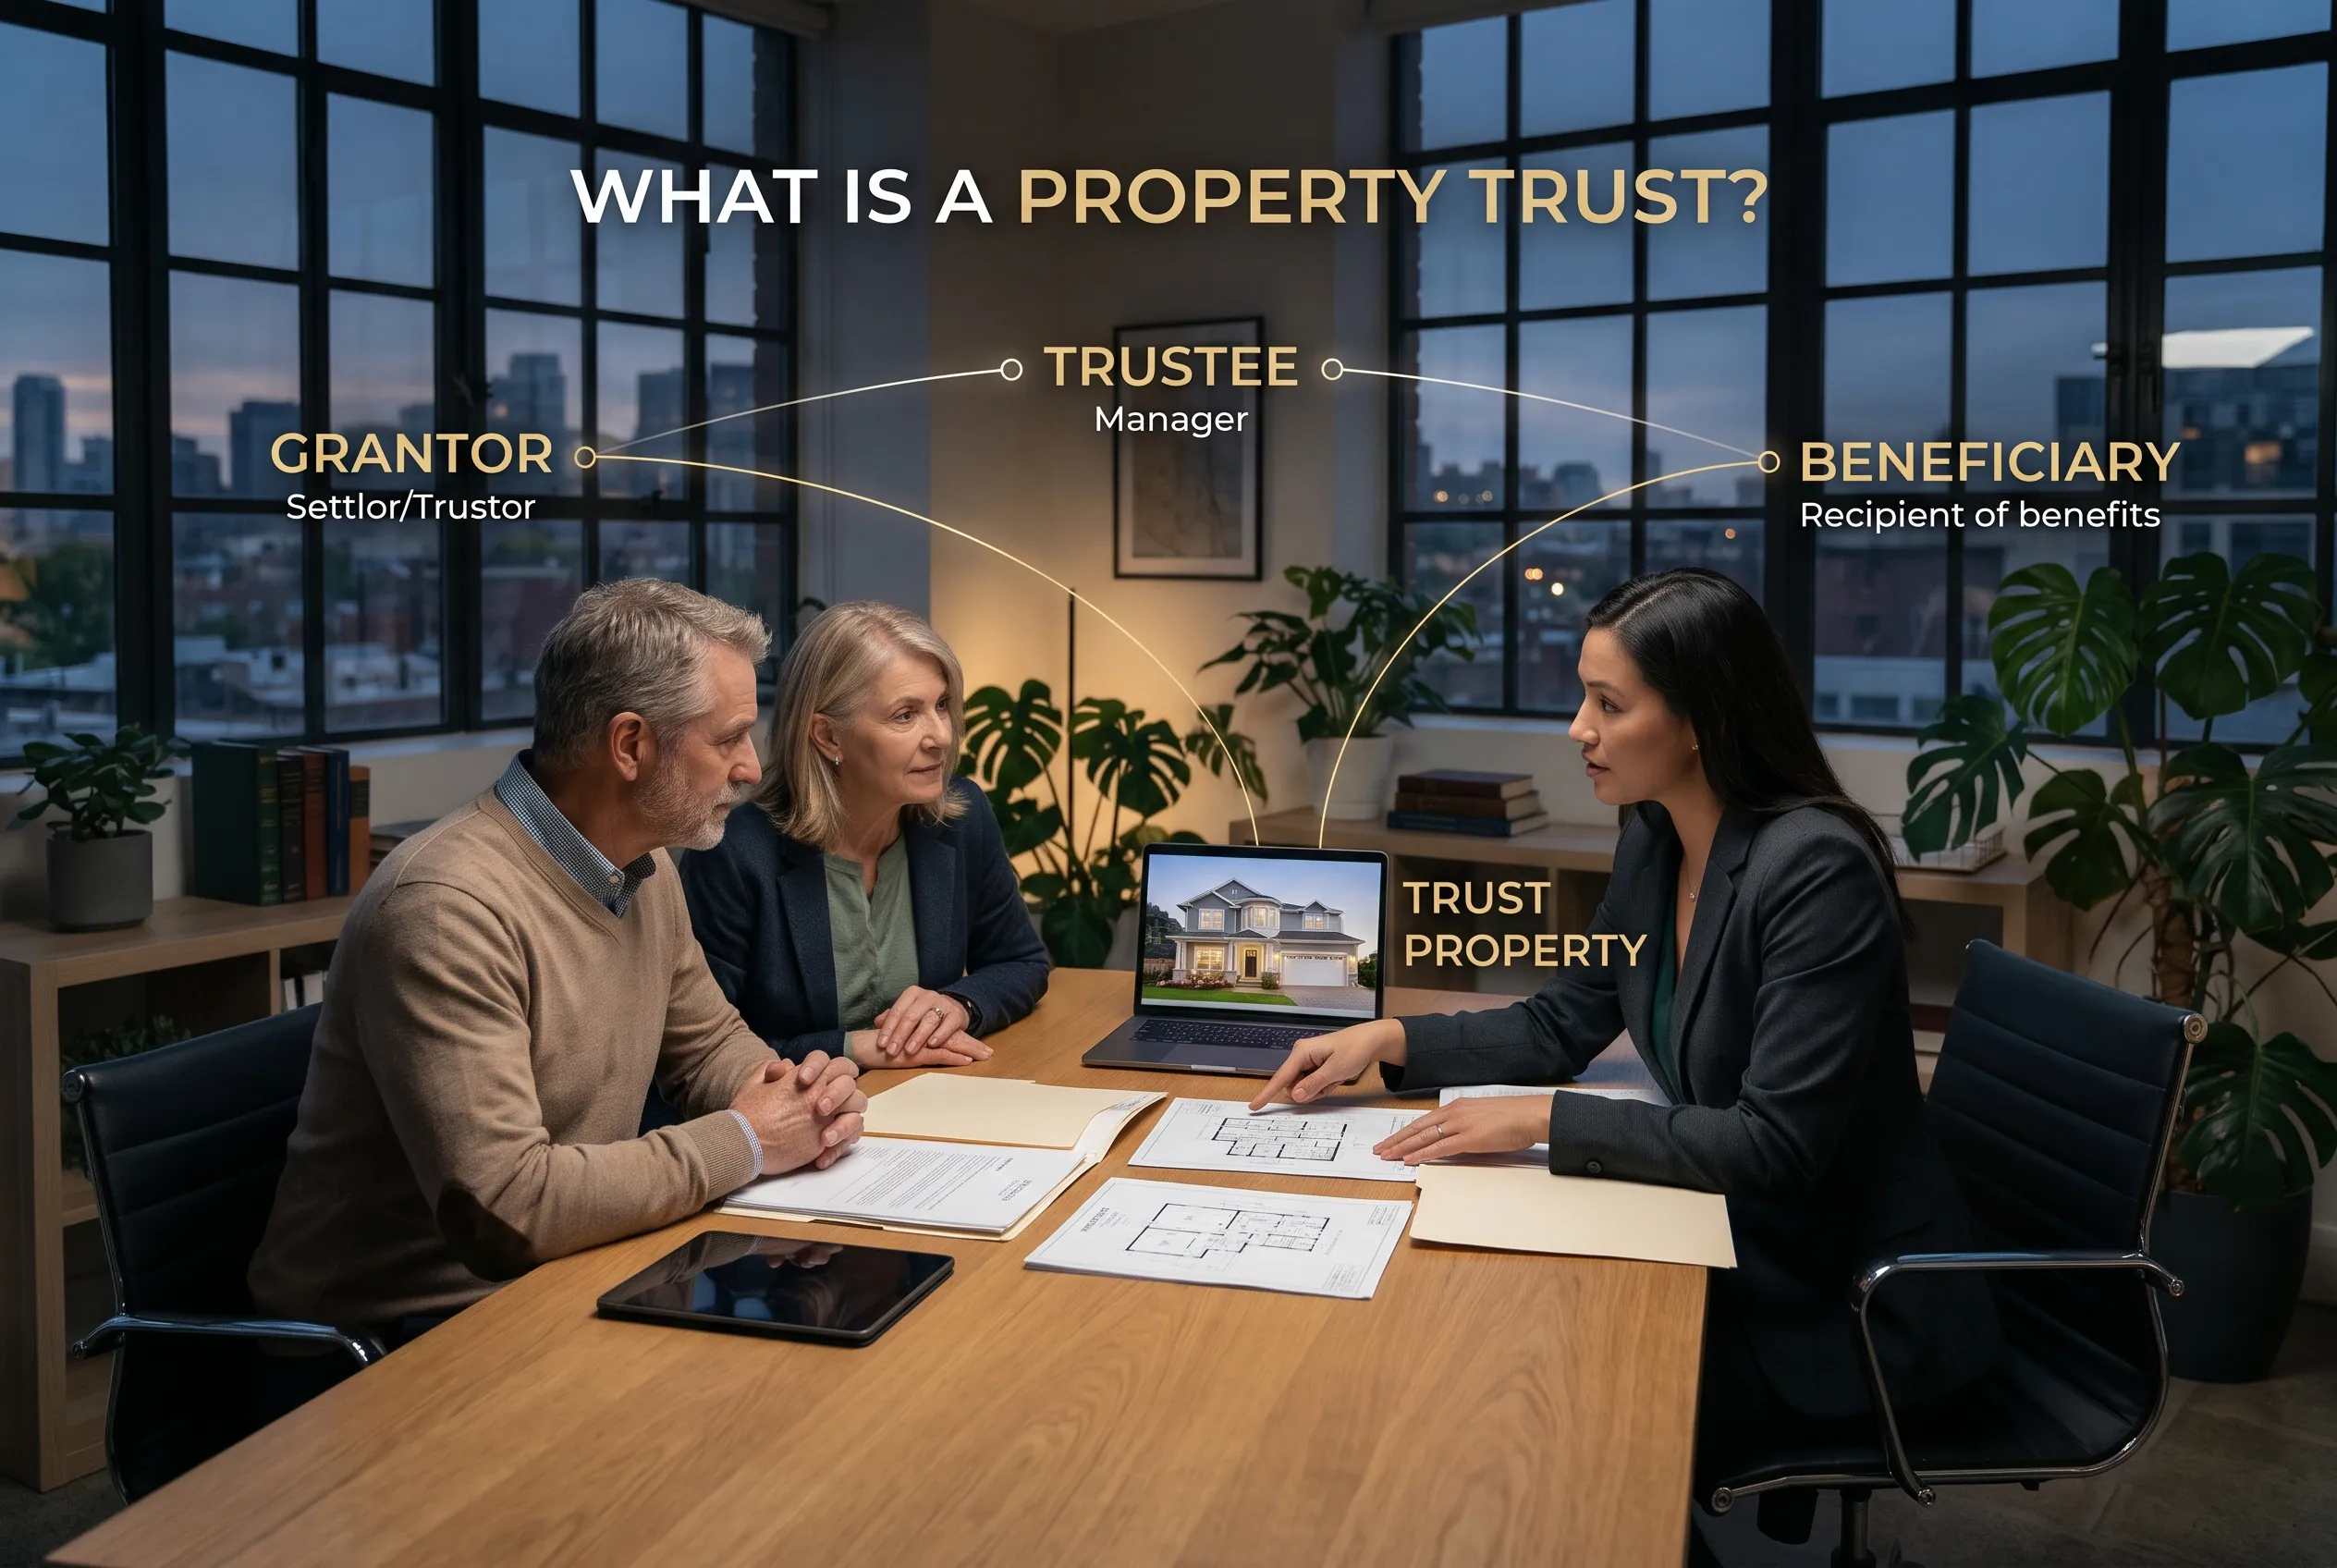 A property trust is a trust arrangement that holds real estate for the benefit of one or more people. The trust agreement explains who manages the property, who benefits from it, and what happens under different circumstances, including the creator’s death or incapacity.
The term property trust does not describe one standardized US c. Different trusts have different rules, costs, and purposes.
Three main roles help explain how a trust works:
- Grantor: The person who creates the trust and places property or other assets into it. This person is also called the settlor or trustor.
- Trustee: The person or institution responsible for managing the trust property according to its terms.
- Beneficiary: The person who receives benefits from the trust, such as the right to use a property or receive its proceeds.
In a common revocable living trust arrangement, a homeowner can create the trust, serve as its initial trustee, and continue living in the house. The homeowner can also name a successor trustee to take over if the homeowner dies or becomes unable to manage the property.
According to the Consumer Financial Protection Bureau’s explanation of revocable living trusts, the creator generally retains control over assets held in this type of trust and can name the people who receive them later.
A property trust is different from a real estate investment trust (REIT). A REIT is an investment structure through which investors can gain exposure to income-producing real estate. A property trust used for estate planning is primarily concerned with holding, managing, or transferring property under agreed legal terms.
How Does a Property Trust Work?
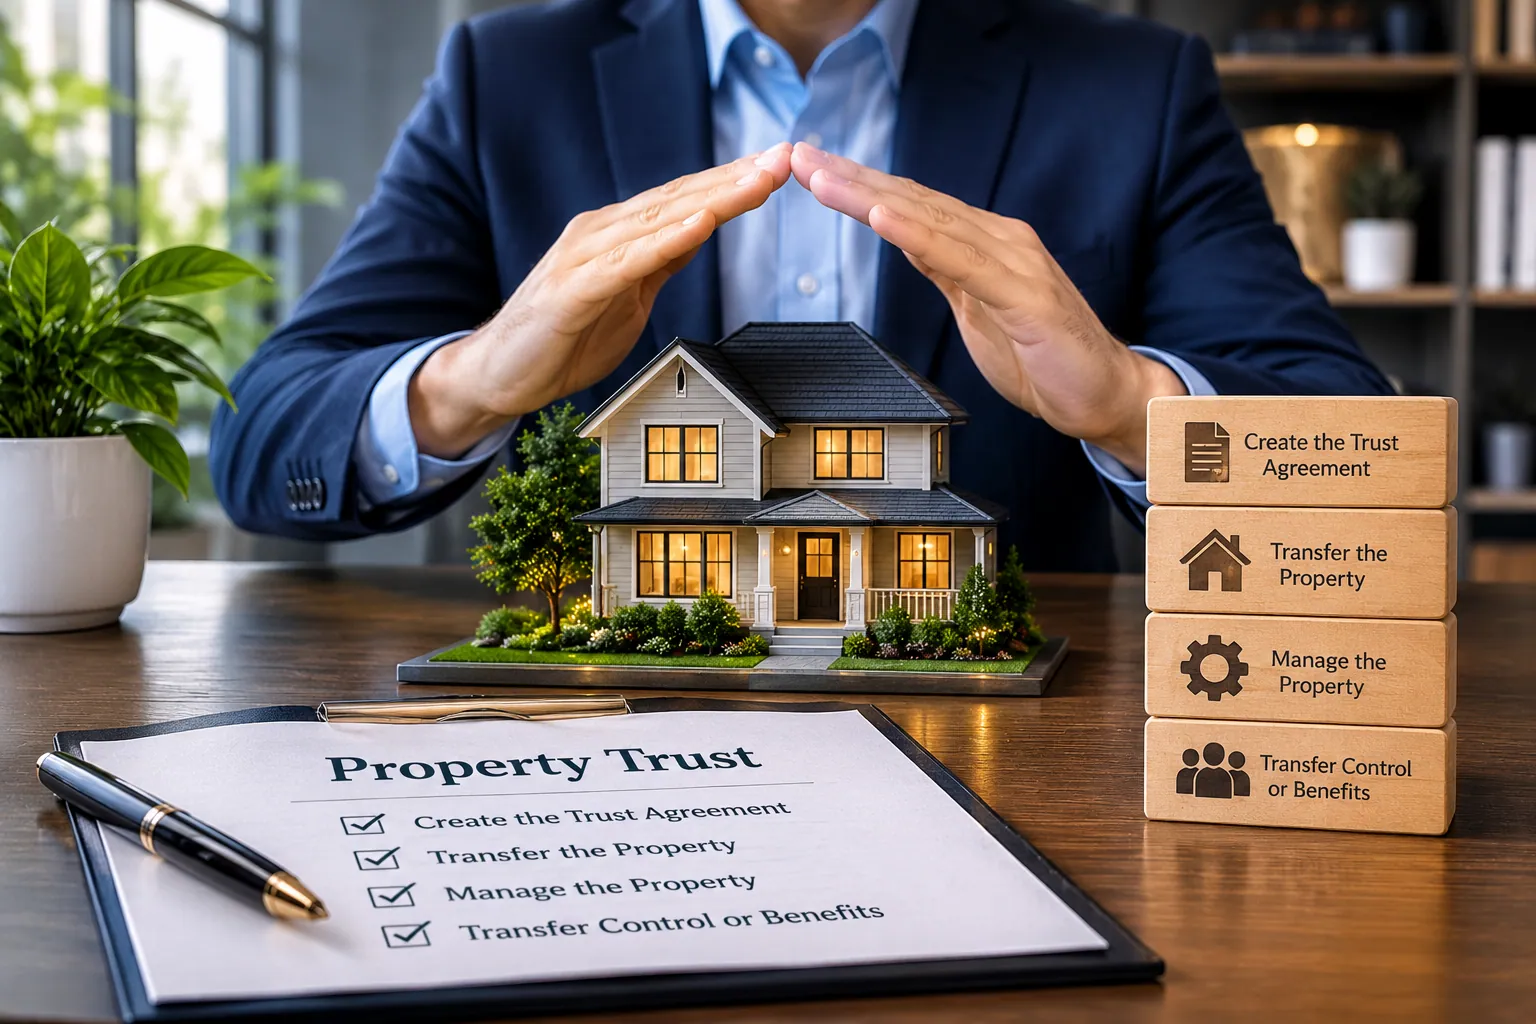 A property trust works by setting rules for managing an asset and transferring the appropriate ownership interests into the trust. The trustee then manages that asset according to the trust agreement.
Suppose you own a house and want your daughter to receive it after your death. You might create a revocable living trust, transfer the house into it, and name yourself as the initial trustee.
You could continue living in the house and managing it under the trust’s terms. You could also name a successor trustee and specify how the house should be handled after your death.
The process generally involves four parts.
- Creating the trust agreement
The agreement identifies the trustee, beneficiaries, management powers, and distribution instructions. It should match your intentions and the requirements of the state where the property is located.
- Transferring the property
Creating the document does not necessarily place your house in the trust. The ownership records generally need to be changed through an appropriate deed or other transfer document.
- Managing the property
The trustee manages the property under the trust’s rules. Depending on the agreement, this may include arranging repairs, paying expenses, maintaining records, or eventually selling the property.
- Transferring control or benefits
If the original trustee dies or becomes incapacitated, a properly appointed successor trustee may take over. After the original owner’s death, the successor trustee generally follows the trust’s instructions for distributing or managing the property.
The important point is that a trust document and a completed property transfer are not the same thing. The CFPB warns that a living trust does not control assets that have not been placed into it.
If you leave your house outside the trust, it may still need to pass through probate, depending on your ownership arrangement and state law.
What Are the Main Types of Property Trusts?
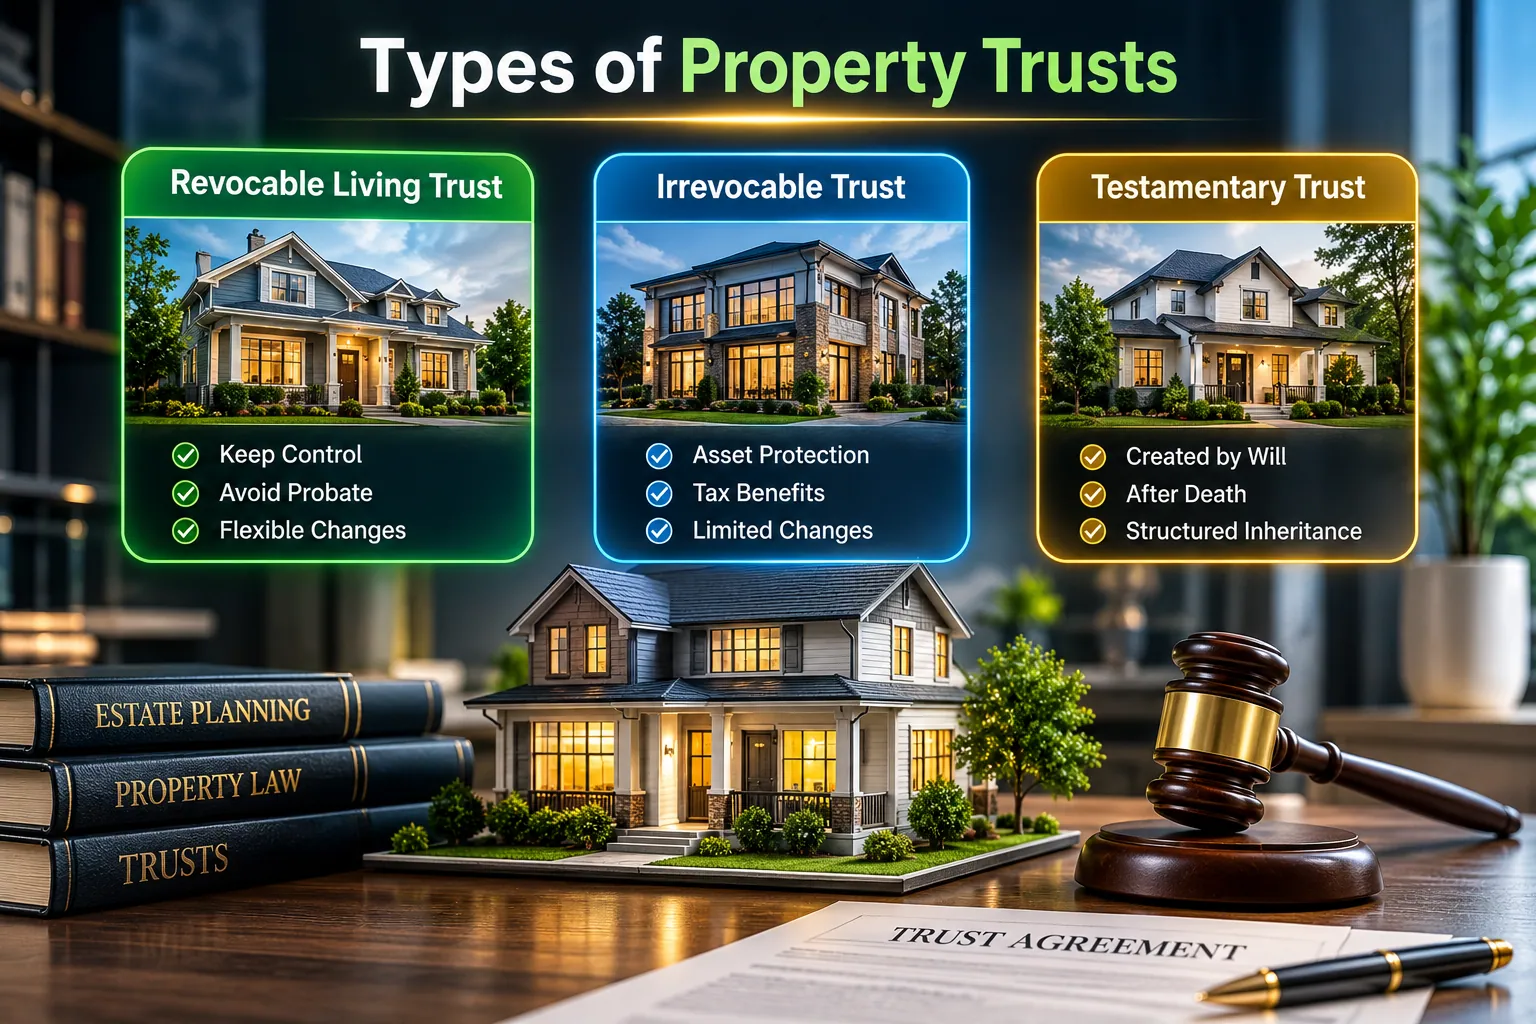 Three common arrangements to understand are revocable living trusts, irrevocable trusts, and testamentary trusts. They serve different purposes, and not all three are the same type of legal classification.
1. Revocable Living Trust
A revocable living trust is created during the grantor’s lifetime and can generally be changed or canceled by the grantor, subject to the trust’s terms and applicable law.
It is often considered by homeowners who want to:
- Keep managing their property during their lifetime.
- Make arrangements for someone else to manage it if they become incapacitated.
- Help their beneficiaries avoid probate for property properly transferred into the trust.
- Specify how their property should be distributed after death.
The main advantage is flexibility. You can generally change beneficiaries, update instructions, or remove property from the trust while you have the legal capacity and authority to do so.
The limitation is that retaining control usually means you have not given up all ownership-related financial rights. A revocable trust generally does not shield your house from your own creditors simply because the property is held in the trust.
It also does not automatically remove the property from your taxable estate.
2. Irrevocable Trust
An irrevocable trust generally cannot be changed or canceled freely by its creator. The precise rules depend on the trust agreement and applicable state law.
Some homeowners consider an irrevocable trust for specialized estate planning, including certain tax or asset-protection goals.
However, these possible benefits involve trade-offs. You may give up important rights over the property, including the ability to change beneficiaries or take the asset back whenever you choose.
An irrevocable trust does not automatically reduce taxes or prevent creditors from reaching property. The result depends on the trust’s terms, the rights you retain, the timing of the transfer, and the applicable laws.
This option deserves careful legal and tax review before you transfer a home into it.
3. Testamentary Trust
A testamentary trust is created through a will and generally begins after the will-maker dies.
For example, a parent might direct through a will that a house or sale proceeds be held in trust for a child until the child reaches a specified age.
This can help structure inheritance for people who may not be ready to manage property or money directly.
However, a testamentary trust is not the same as a living trust. Because it is created through a will, the will generally goes through probate before the trust is established, subject to applicable law and any relevant exceptions.
The IRS’s trust guidance explains the distinction between trusts created during a person’s lifetime and those created by a will.
What Are the Benefits of Putting a House in a Trust?
Putting a house in a trust may help you manage property, plan for incapacity, and make inheritance instructions easier to carry out. The most useful benefit depends on the problem you are trying to solve.
Avoiding probate
Probate is the legal process used to handle a deceased person’s estate. Depending on the circumstances, it may involve validating a will, identifying assets, paying valid claims, and distributing property.
A properly funded living trust can allow the successor trustee to manage or distribute the house without putting that particular asset through probate.
This may reduce delays and provide more privacy than a probate process that makes estate information available through public records.
However, a trust does not automatically avoid probate for assets left outside it. Other estate assets may still require probate, and the rules vary by state.
Planning for incapacity
A serious illness or injury may leave a homeowner unable to manage financial affairs.
If the house is properly held in a trust and the agreement provides for a successor trustee, that person may be able to manage the property without waiting for a separate court process, subject to the trust’s terms and applicable law.
This can help with practical matters such as repairs, insurance, property taxes, and other ongoing expenses.
A trust is not a complete substitute for an estate plan. You may also need appropriate financial and health care powers of attorney and other documents.
Organizing inheritance
A trust allows you to provide instructions about who receives property and how it should be managed.
For example, you may want a surviving spouse to continue using the family home before the property passes to your children. Depending on the trust structure and applicable law, a trust may help organize those interests.
Detailed arrangements need careful drafting because vague instructions or unclear beneficiary rights can lead to disputes.
Managing property over time
A trust can establish who is responsible for managing the property and what should happen if the original trustee cannot continue.
This may be useful for families with several beneficiaries, rental properties, or a home that needs to be managed before it is sold or distributed.
Still, a trust creates responsibilities as well as benefits. Someone must follow its instructions, maintain records, and handle ongoing property expenses.
What Are the Downsides and Costs of a Property Trust?
The main downsides are setup expenses, additional paperwork, transfer requirements, and the possibility of choosing a trust that does not match your goal. A trust can be useful, but it is not automatically worth the cost for every homeowner.
Setup and professional fees
The total cost may include preparing the trust, reviewing existing property ownership, preparing a deed, recording documents, and obtaining legal or tax advice.
Online document packages can cost less than a customized estate plan, but they may not provide the same level of individual review.
For a current price example, LegalZoom’s estate-plan pricing page lists its Basic Trust package at $399 and Premium Trust package at $549. The Premium package includes attorney consultations for the first year and states that the service renews at $199 per year afterward. These are provider-advertised prices, not quotes for every customer or a complete estimate of property-transfer costs.
For comparison, Legal Templates reported in a 2026 estate-planning cost study that the median fee for a single revocable living trust among 226 surveyed law firms was $2,475. The study reported a middle 50% range of $1,600 to $3,000.
These figures measure different services and come from different sources. They should not be treated as a like-for-like comparison or as a universal market price.
Before paying, check exactly what the service includes. Deed preparation, county recording fees, extra legal work, and ongoing administration may cost more.
Less flexibility with some trusts
A revocable trust generally offers flexibility, but an irrevocable trust may limit your ability to take the property back or change its terms.
Transferring a home into an irrevocable trust without understanding those limitations can create a difficult and expensive problem later.
No automatic tax savings
A trust may affect estate administration, but that does not mean it automatically reduces taxes.
The IRS generally treats a revocable living trust as a grantor trust for federal income-tax purposes. This means the grantor is generally treated as the owner for income-tax purposes while the relevant grantor-trust rules apply.
Some irrevocable trusts may have different tax consequences, but those consequences depend on the specific arrangement.
You should distinguish income tax, estate tax, gift tax, and state property-tax rules. Each follows its own requirements.
More paperwork and ongoing responsibility
The property records, insurance arrangements, and trust documents need to reflect the intended ownership structure.
If you buy another property or change your estate plan, you may need further legal work.
A trust can also create administrative duties for a successor trustee. That person should know where the documents are kept and understand what the agreement requires.
How Do You Put Property Into a Trust?
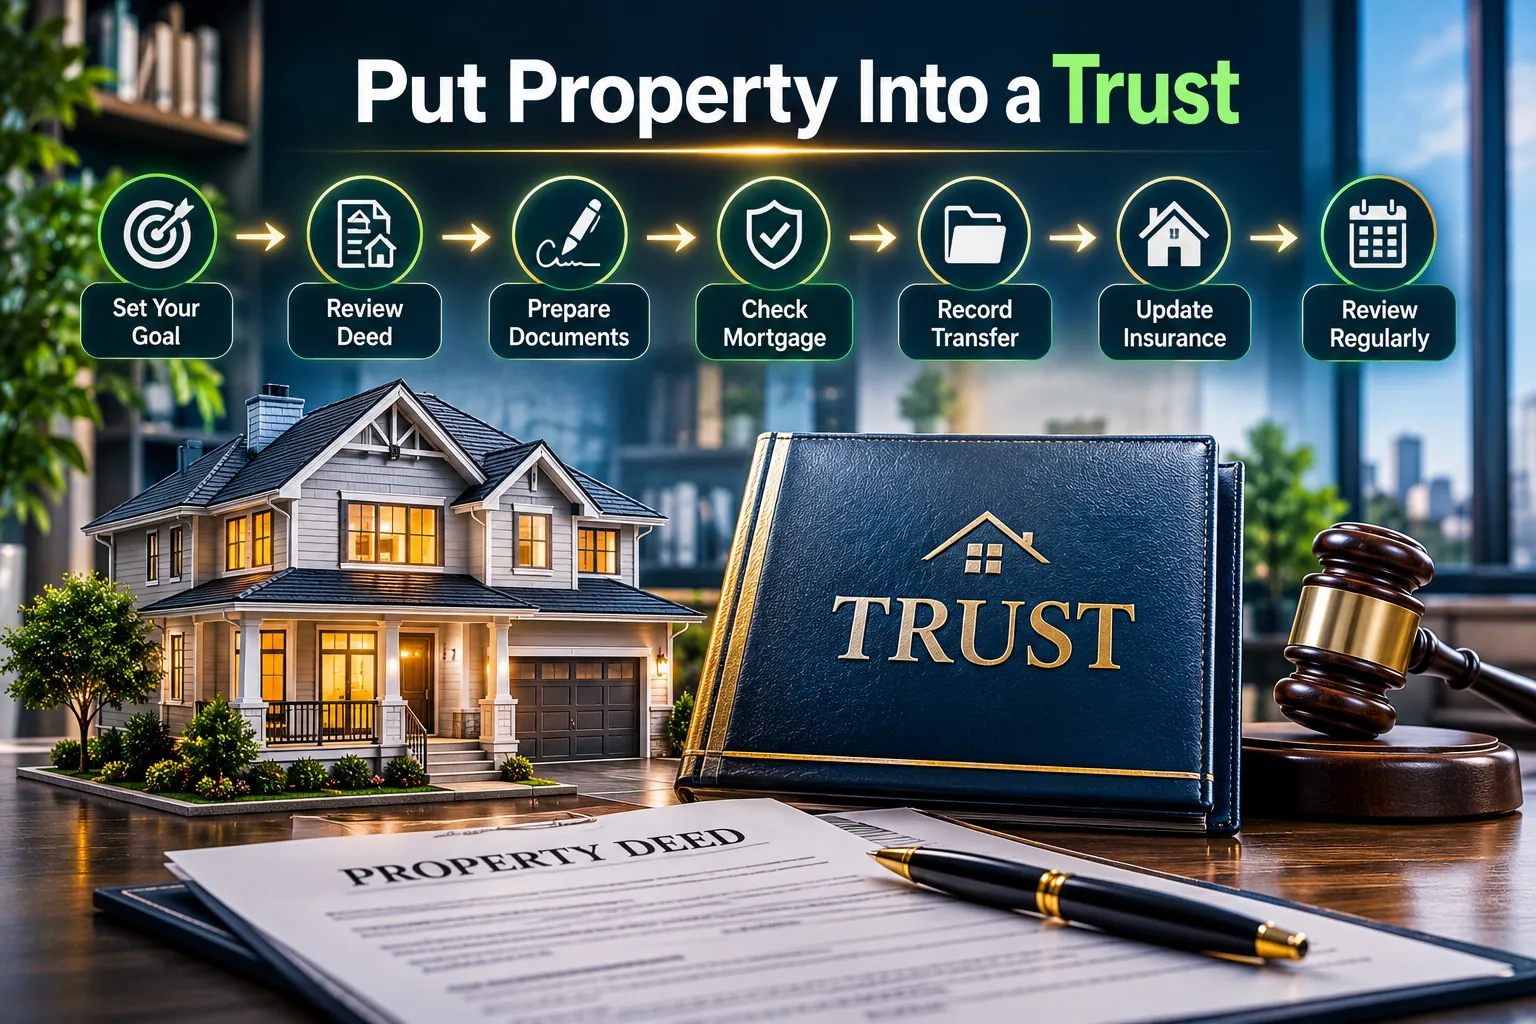 The exact process depends on the property’s location, ownership, mortgage, and state law. The following steps provide a general framework for a US homeowner.
Step 1: Identify your goal
Decide what you want the trust to accomplish. You might want to plan for incapacity, reduce probate exposure, organize inheritance, or address a more specialized estate-planning need.
Your goal matters because a revocable living trust may suit one situation while another structure may be more appropriate for a different legal or tax objective.
Step 2: Review the current property deed
Check how the house is currently titled and who owns it. Joint ownership, existing liens, marital property rules, and other restrictions may affect the transfer.
If you cannot find the current deed, check the relevant county’s land records or contact the local recorder’s office.
Step 3: Prepare the trust and transfer document
A trust agreement sets the rules, while an appropriate deed or other legal document transfers ownership.
The correct wording, signatures, notarization requirements, and recording process depend on state and local law. A qualified estate-planning attorney can help make sure the documents match the intended arrangement.
Step 4: Check the mortgage before transferring
If your home has a mortgage, review the loan documents and applicable transfer rules before changing the title.
Federal law under 12 U.S.C. § 1701j-3 limits the enforcement of certain due-on-sale clauses for qualifying transfers into an inter vivos trust. One important condition is that the borrower remains a beneficiary and the transfer does not relate to a transfer of occupancy rights.
This is a specific legal exception, not a blanket exemption for every property transfer or loan. Check whether your situation meets the applicable conditions and whether your lender needs documentation.
Step 5: Complete the recording process
Follow the local requirements for signing and recording the transfer document. Keep copies of the recorded deed, trust agreement, and any other relevant paperwork.
Do not assume the transfer is complete just because you signed the trust. Verify the recorded title and confirm that the ownership records reflect the intended arrangement.
Step 6: Review insurance and property records
Contact your homeowners insurance provider to confirm whether the policy or named insured details need to change. Keep mortgage, tax, and property records consistent with the trust arrangement where required.
The purpose is to reduce confusion when a claim occurs or a successor trustee needs to manage the home.
Step 7: Review the arrangement periodically
Review the trust after major life changes, property purchases, marriages, divorces, or changes in your wishes.
If you buy another property, do not assume it automatically becomes part of an existing trust. Follow the required transfer steps for that asset.
Property Trust vs. Will: Which Option Fits Your Needs?
A will and a property trust can work together, but they perform different roles. A will states what should happen to property under its terms, while a living trust can hold and manage property during your lifetime and provide instructions for its later management or distribution.
| Feature | Revocable living trust | Will |
| Works during your lifetime | Yes, for assets held in the trust | Generally does not manage assets during your lifetime |
| Can help avoid probate | For properly transferred trust assets | Property passing through a will generally goes through probate |
| Can provide instructions after death | Yes | Yes |
| Requires property transfer into the arrangement | Generally yes, for real estate to be held in the trust | No equivalent lifetime transfer is required just to write the will |
| Can help plan for incapacity | Through appropriate successor-trustee provisions | Generally requires separate planning documents for lifetime incapacity |
| Costs and administration | Setup and ongoing responsibilities may apply | Often simpler to prepare, though costs and complexity vary |
Some estate plans use both documents. A pour-over will, for example, directs certain assets left outside a living trust into the trust after death. Those assets may still need to go through probate before they are transferred.
A will may be sufficient for someone with straightforward needs. A trust may be more useful when avoiding probate for particular assets, planning for incapacity, or managing a more complex inheritance is a priority.
Neither option is automatically right for everyone. Your state’s laws, property ownership, family circumstances, and the cost of each approach matter.
Can Someone Take Your House If It Is in a Trust?
Yes, a home held in a trust can still be subject to certain claims and legal obligations. A trust does not make the property untouchable.
Consider the main situations separately.
Mortgage payments: If the home secures a mortgage, placing it in a trust does not erase the debt or the lender’s security interest.
Property taxes: Any applicable property-tax obligations remain important. A trust should not be treated as a way to ignore them.
Creditor claims: A revocable living trust generally does not protect the grantor’s assets from the grantor’s own creditors merely because the assets are held in the trust. The grantor typically retains control and the benefits of ownership.
Irrevocable trusts: Some arrangements may offer protection under particular circumstances, but that depends on state law, the trust’s terms, the rights retained by the creator, and the timing of the transfer. Moving assets to defeat existing creditors may create serious legal problems.
If creditor protection is your main goal, do not transfer your home based on a general promise that a trust will protect it. Ask an estate-planning attorney to review your situation before making an irreversible transfer.
A Practical Checklist Before Choosing a Property Trust
Before deciding whether to put your house into a trust, work through these questions:
- What is your main goal? Identify whether you want probate planning, incapacity planning, inheritance instructions, or another specific result.
- What will it cost? Compare the complete service, transfer expenses, recording fees, and possible ongoing costs.
- What does your state require? Check the rules that apply to the property’s location.
- What about your mortgage and insurance? Verify applicable transfer conditions and any documentation you need.
- Will you retain control? Understand the difference between revocable and irrevocable arrangements.
- Has the property actually been transferred? Confirm the recorded title and keep the relevant documents.
- Do you need specialist help? Get appropriate legal or tax guidance if your goal involves creditor protection, Medicaid eligibility, complex inheritance, or significant tax consequences.
These checks can help you avoid paying for a trust that does not achieve your intended result.
Frequently Asked Questions
Is it a good idea to put your house in a trust?
It can be a good option if you want to plan for incapacity, help avoid probate for the property, or organize how your home passes to beneficiaries. It may be less useful if your estate is simple and the setup costs outweigh the benefits. State law and your personal goals should guide the decision.
What are the three types of property trusts?
Three common arrangements are revocable living trusts, irrevocable trusts, and testamentary trusts. Revocable and irrevocable describe whether a trust can generally be changed or canceled, while testamentary describes a trust created through a will after the will-maker’s death.
Can someone take your house if it is in a trust?
A trust does not automatically protect a house against every claim. Mortgage obligations, property taxes, liens, and certain creditor claims may still apply. The level of protection depends on the trust type, its terms, applicable law, and the circumstances of the claim.
Does a property trust avoid taxes?
A property trust does not automatically eliminate taxes. A revocable living trust is generally treated as a grantor trust for federal income-tax purposes. Estate, gift, and state property-tax consequences depend on the arrangement and applicable rules.
Make the Decision Based on Your Goal
A property trust can be a useful part of an estate plan, but the decision should start with what you want to achieve. If your priorities are probate planning, incapacity planning, or inheritance management, compare an appropriate trust with a will and other options available under your state’s law.
Before paying for a trust, confirm the total cost, understand the level of control you will retain, and check how the property must be transferred. For more complex tax, creditor-protection, or Medicaid planning, obtain advice from a qualified professional who understands the relevant state rules.
The aim is not simply to put your house in a trust. It is to choose an arrangement that fits your goals, understand its limits, and ensure the property records and legal documents support the plan.
Disclaimer
This article provides general financial education, not personalized financial, investment, legal, or tax advice. Laws, costs, trust terms, and outcomes vary by state and individual circumstances, and results are not guaranteed. For property transfers or complex tax, Medicaid, or creditor-protection questions, consult a qualified estate-planning attorney or tax professional.